Variant Insurance Group is a licensed independent insurance agency in Minnesota. [CONFIRM license #.]
Get a Quote
Variant Insurance Group is a licensed independent insurance agency serving Minnesota families and businesses.
From our office in Maple Plain, our team works with many of Minnesota's top-rated carriers so your home, auto, life, and business coverage fits your real needs. We serve families and businesses across Minnesota.
New title
New title
Walker sits right in the middle of one of Louisiana's busiest commuter corridors. If you drive I-12 or Highway 447 to work, you already know the congestion, the close calls, and the way a summer storm can turn your windshield into a target range for broken branches. What you might not know is whether your auto insurance policy is actually built to handle those risks. For drivers in Walker and across Livingston Parish, understanding your coverage isn't just a paperwork exercise: it's a financial safety net that can mean the difference between a manageable inconvenience and a devastating out-of-pocket expense. Louisiana's insurance requirements are among the lowest in the country, and that creates a false sense of security for anyone carrying only the state minimum. Pair that with a high percentage of uninsured motorists on local roads and a climate that regularly sends debris flying across highways, and you've got a recipe for trouble. This guide breaks down what Walker drivers specifically need to understand about their auto insurance, from minimum liability limits and commuter exposure to uninsured motorist protection and comprehensive claims after storms. Whether you're a daily I-12 commuter or you mostly stick to local roads around Walker, the right policy structure matters more here than in most places.
Navigating Auto Insurance in Walker: The Basics
Livingston Parish has grown rapidly over the past two decades, and Walker has absorbed much of that growth. More residents means more vehicles on roads that weren't always designed for the volume they now carry. That growth directly affects your auto insurance: more traffic leads to more accidents, which drives up claim frequency and, eventually, premiums. Understanding your baseline coverage is the first step toward protecting yourself.
Understanding Louisiana's 15/30/25 Minimum Requirements
Louisiana requires every driver to carry liability insurance with minimum limits of 15/30/25. That breaks down to $15,000 in bodily injury coverage per person, $30,000 per accident, and $25,000 in property damage per accident. These numbers haven't changed in years, and they reflect a time when medical bills and vehicle values were far lower than they are today.
To put this in perspective: a single ER visit after a moderate car accident can easily exceed $15,000 before any surgery, rehabilitation, or specialist care enters the picture. If you cause an accident that injures two people, your $30,000 cap could be exhausted before either person is fully treated. The $25,000 property damage limit barely covers the value of an average new car in 2026, let alone a truck or SUV.
Why Minimum Limits Often Fall Short in Livingston Parish
Walker isn't a low-cost-of-living bubble. Vehicles on local roads include newer trucks, SUVs, and family vehicles that commonly cost $35,000 to $55,000. If you rear-end someone's late-model pickup and you're carrying only $25,000 in property damage coverage, you're personally responsible for the difference.
The real risk is a lawsuit. Louisiana allows injured parties to sue at-fault drivers for amounts exceeding their policy limits. That means your savings, your home equity, and even future wages could be on the table. For most Walker families, carrying 50/100/50 or even 100/300/100 limits costs only modestly more per month but provides dramatically better protection. An agency like Chabert Insurance: The Ehrhardt Agency can walk you through the actual cost difference, which is often smaller than people expect.
Commuting Risks on I-12 and Highway 447
Your daily commute is the single biggest factor in your accident exposure. For Walker residents, that commute almost always involves I-12, Highway 447, or both. These aren't quiet country roads: they're high-speed, high-volume corridors with real risk profiles.
High-Volume Traffic and Rear-End Collision Exposure
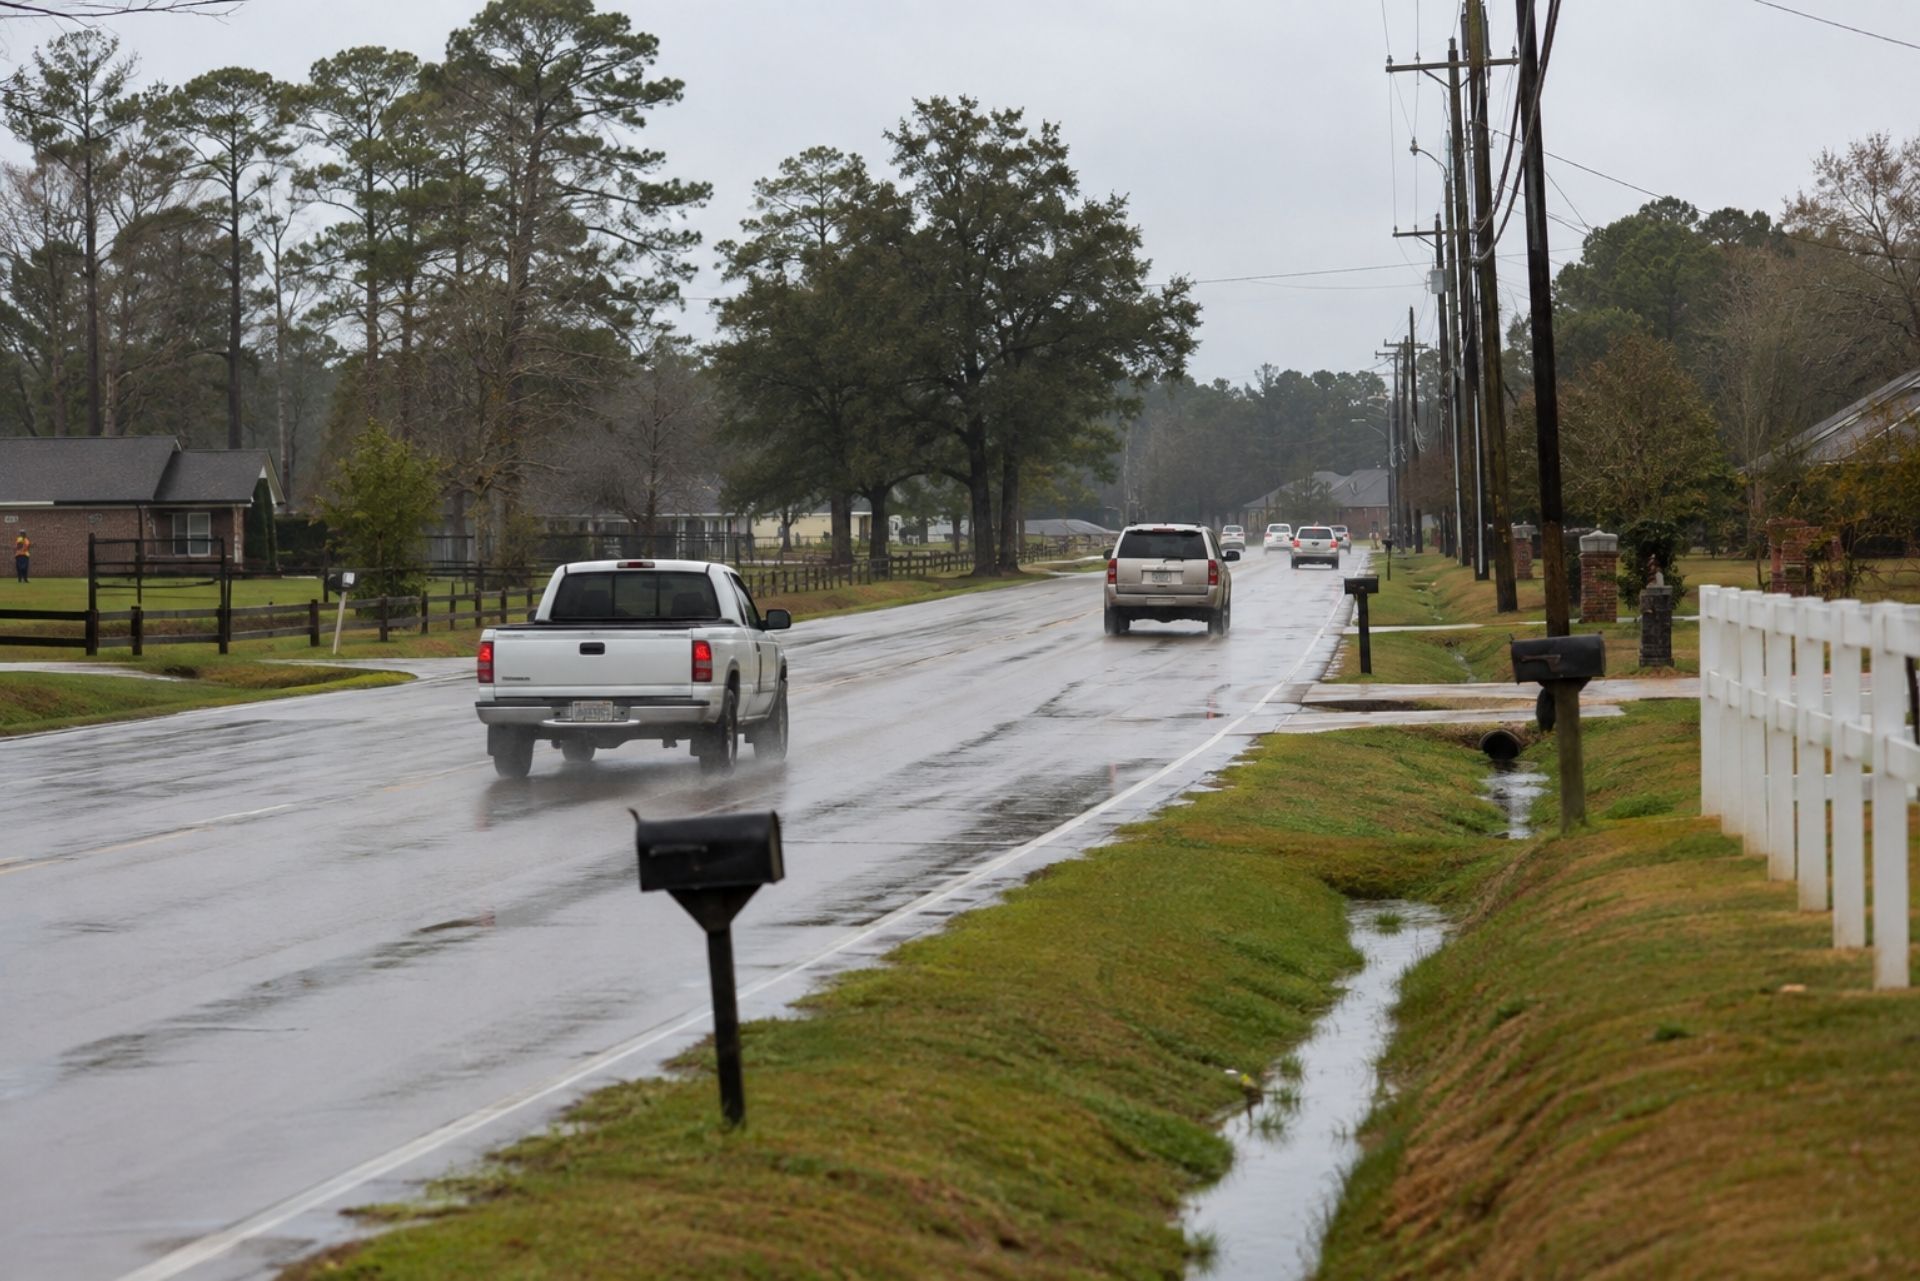
Highway 447 in Walker carries between 10,000 and 25,000 vehicles daily, and that number climbs during peak commute hours. I-12 connects Baton Rouge to the North Shore, funneling workers, commercial trucks, and through-traffic into a corridor that frequently backs up near the Walker and Denham Springs exits.
Rear-end collisions are the most common accident type on these routes. Stop-and-go traffic during morning and evening rush hours creates constant braking situations. Distracted driving compounds the problem. A rear-end collision at even 25 mph can cause whiplash injuries that require months of treatment, and the at-fault driver's minimum liability often won't cover the full cost.
Comparison: Minimum Liability vs. Recommended Commuter Limits
Here's a practical look at how minimum limits stack up against what most insurance professionals recommend for daily commuters:
| Coverage Type | Louisiana Minimum | Recommended for Commuters |
|---|---|---|
| Bodily Injury (per person) | $15,000 | $100,000 |
| Bodily Injury (per accident) | $30,000 | $300,000 |
| Property Damage | $25,000 | $100,000 |
| Uninsured Motorist | Not required | $100,000/$300,000 |
| Collision Deductible | Not required | $500 - $1,000 |
| Comprehensive Deductible | Not required | $500 - $1,000 |
The premium difference between minimum and recommended coverage varies, but for many Walker drivers it's $40 to $80 per month. That's a small price compared to the financial exposure of an underinsured accident on I-12.
The Necessity of Uninsured Motorist (UM) Coverage
Louisiana consistently ranks among the states with the highest percentages of uninsured drivers. Estimates put the number somewhere around 10-13% of motorists on the road without any coverage at all. In a parish like Livingston, where traffic volumes are high and economic pressures are real, the odds of being hit by someone without insurance aren't small.
Protecting Yourself Against Uninsured Drivers in Walker
Uninsured motorist coverage pays for your injuries and damages when the at-fault driver has no insurance or not enough insurance to cover your losses. Louisiana is one of the few states that requires insurers to offer UM coverage, but you can reject it in writing. Many drivers do reject it to save money, and that decision can be catastrophic.
Picture this scenario: you're stopped at a red light on Highway 447 and someone runs into you from behind. They have no insurance. Without UM coverage, you're left paying your own medical bills, lost wages, and vehicle repairs. With UM coverage, your own policy steps in to cover those costs up to your policy limits. For Walker drivers dealing with heavy commuter traffic, UM coverage isn't optional in any practical sense: it's essential.
UM Economic vs. UM Non-Economic Coverage
Louisiana splits UM coverage into two categories, and understanding the difference matters. UM Economic covers tangible losses: medical bills, lost wages, and property damage. UM Non-Economic covers pain and suffering, mental anguish, and loss of enjoyment of life.
You can carry both, or you can reject UM Non-Economic while keeping UM Economic. Some drivers choose this to lower premiums. But if you're seriously injured in an accident with an uninsured driver, pain and suffering damages can represent the largest portion of a fair settlement. Dropping non-economic coverage saves money upfront but limits your recovery options when you need them most. The team at Chabert Insurance: The Ehrhardt Agency can help you understand what you'd actually be giving up before you sign that waiver.
Storm-Debris and Comprehensive Coverage for Local Hazards
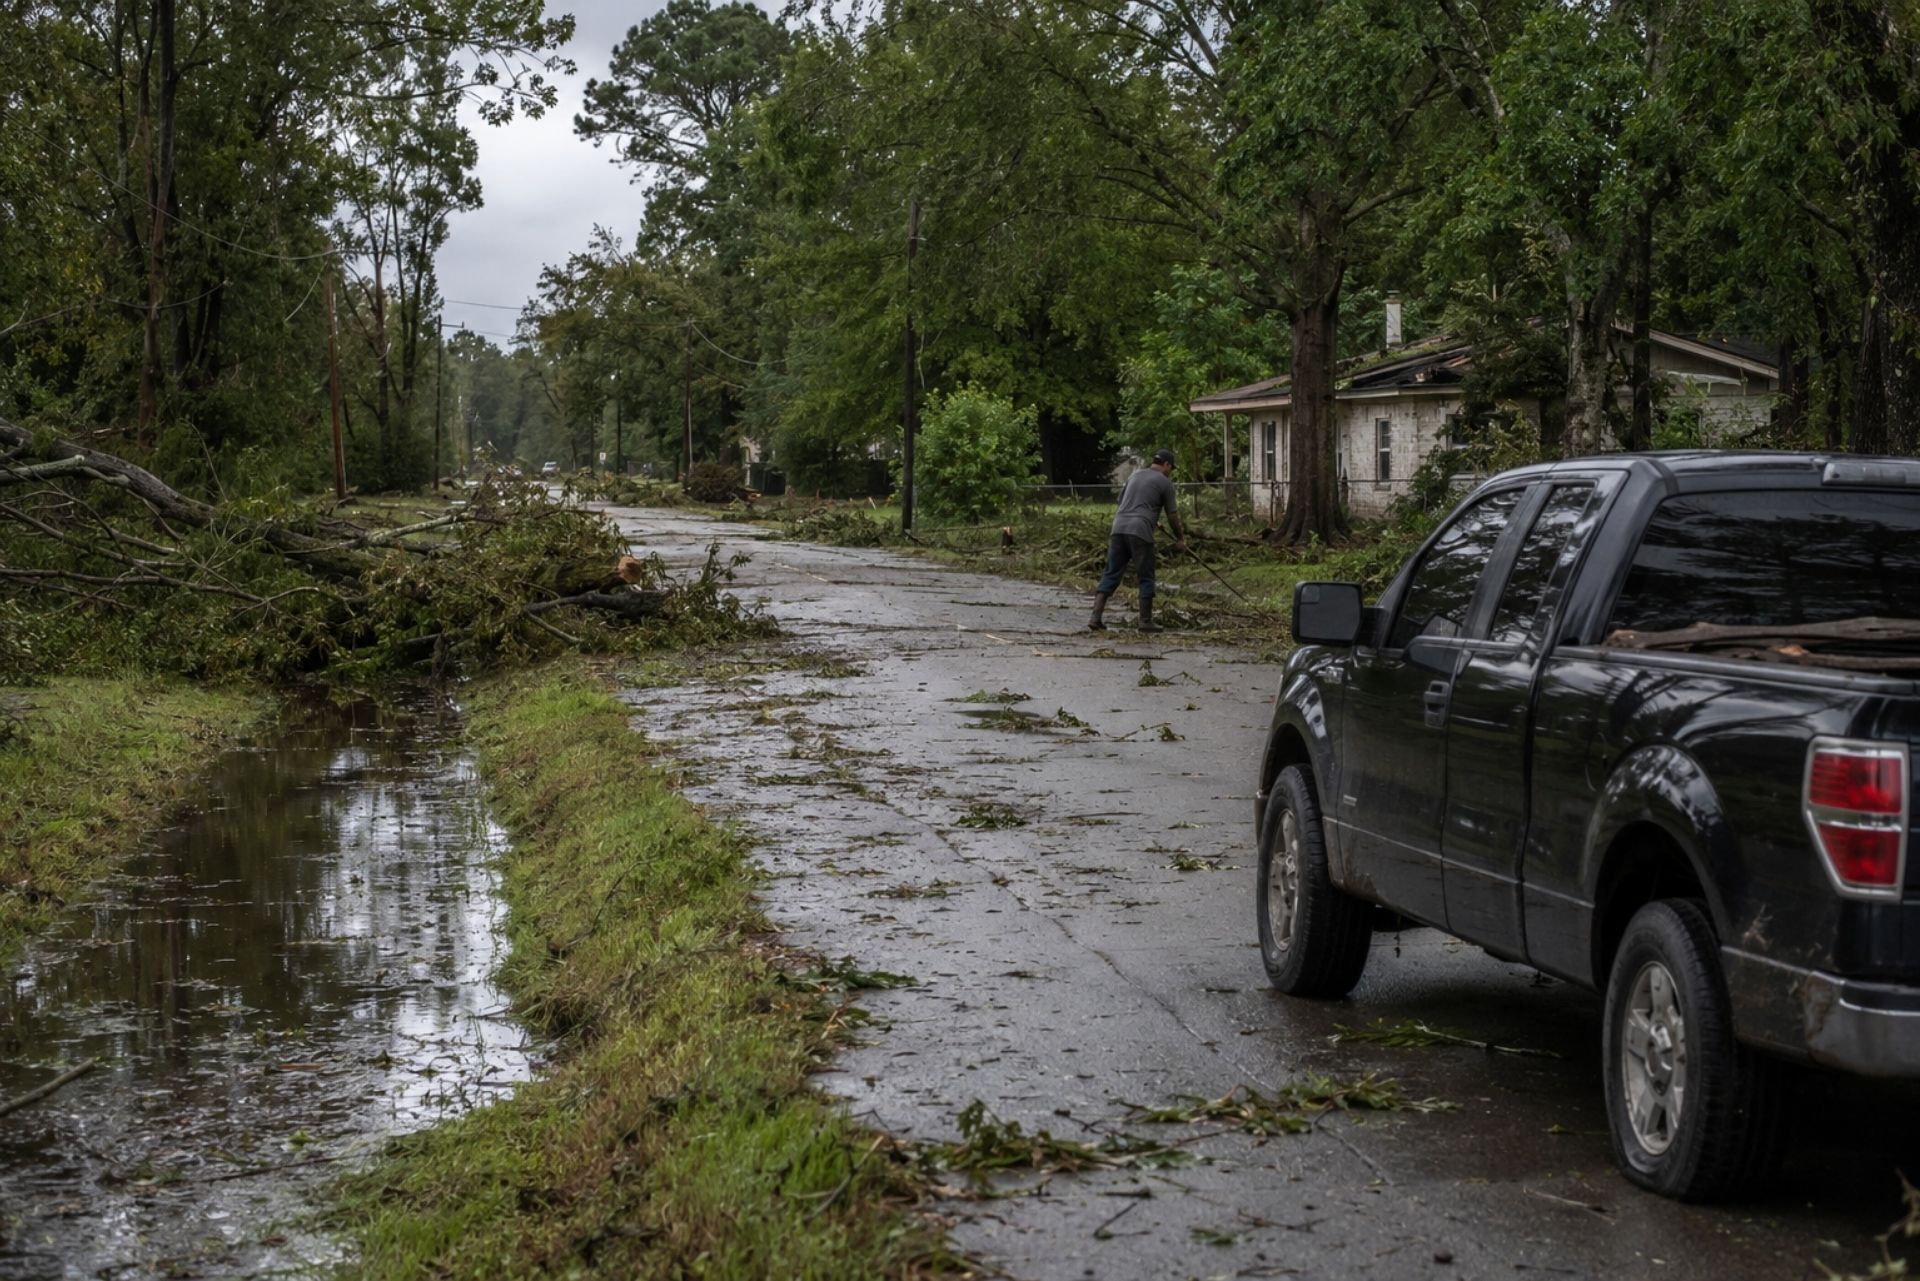
Walker sits in a region that sees tropical storms, heavy thunderstorms, and occasional hurricanes. Trees line many of the parish's roads, and rural stretches of Highway 447 and surrounding routes are particularly vulnerable to fallen limbs and wind-blown debris. Your standard liability policy won't cover any of this damage to your own vehicle.
Dealing with Fallen Limbs and Flying Debris on Rural Roads
A falling tree limb doesn't need hurricane-force winds to total your car. Even a moderate thunderstorm can send branches onto parked vehicles or across roadways. Louisiana insurance officials have clarified guidelines for policyholders affected by tropical storms, and the key takeaway is consistent: comprehensive coverage is what pays for storm-related damage to your vehicle.
If you're financing or leasing your vehicle, your lender almost certainly requires comprehensive coverage. But if you own your car outright, you might have dropped it to save money. In Walker, where storm debris is a recurring reality, going without comprehensive coverage is a gamble that doesn't pay off well. Storm damage to vehicles is one of the most common insurance claims in Louisiana, and having the right coverage in place before storm season starts is the only way to protect yourself.
How Comprehensive Differs from Collision After a Storm
People often confuse comprehensive and collision coverage, especially after a storm. Here's the simple distinction: collision covers damage from hitting another vehicle or object. Comprehensive covers damage from events outside your control: storms, hail, flooding, falling objects, animal strikes, and theft.
If a tree falls on your car while it's parked in your driveway, that's a comprehensive claim. If you swerve to avoid a fallen branch and hit a guardrail, that's a collision claim. The distinction matters because comprehensive and collision apply differently in storm-prone areas, and your deductibles may differ between the two. Some policies also include separate wind and hail deductibles, which can be percentage-based rather than flat-dollar amounts. Check your declarations page or ask your agent to confirm exactly what you're carrying before the next storm hits.
Common Questions from Walker Drivers
FAQ: Practical Answers for Livingston Parish Residents
Does car insurance cover storm damage in Louisiana? Yes, but only if you carry comprehensive coverage. Standard liability won't pay for damage to your own vehicle from storms. Your car insurance can cover storm damage if you've added comprehensive to your policy before the event occurs.
Can I add UM coverage after I've already rejected it? Yes. You can contact your insurer at any time to add uninsured motorist coverage back to your policy. You'll need to complete new paperwork, and the coverage will apply going forward, not retroactively.
How much does it cost to increase from minimum to full coverage in Walker? It depends on your driving record, vehicle, and age, but most Walker drivers see increases of $40 to $80 per month when moving from bare-minimum liability to a policy with higher limits, UM coverage, and comprehensive/collision.
Is flood damage covered under comprehensive auto insurance? Yes. Unlike homeowners insurance, which requires a separate flood policy, auto comprehensive coverage does include flood damage. Given Walker's proximity to waterways and its history of flooding, this is a significant benefit.
Do I need collision coverage if my car is paid off? It's not legally required, but consider your car's value. If you couldn't afford to replace it out of pocket, collision coverage is worth keeping. Once your vehicle's value drops below $3,000 to $4,000, the math starts to shift.
Making the Right Choice for Your Commute
Walker drivers face a specific combination of risks that most generic insurance advice doesn't address. High-volume commutes on I-12 and Highway 447, a significant uninsured motorist population, and regular storm exposure all demand coverage that goes well beyond Louisiana's minimum requirements.
The smartest approach is to match your coverage to your actual exposure. If you commute daily, higher liability and UM limits protect you from the financial fallout of a serious accident. If you park outside or drive tree-lined roads, comprehensive coverage keeps storm debris from becoming a financial crisis. And if you're carrying only the state minimum, you're essentially betting that nothing serious will ever happen on some of the busiest roads in Livingston Parish.
A local agency familiar with Walker's specific risks can help you build a policy that fits your budget without leaving dangerous gaps. Chabert Insurance: The Ehrhardt Agency works with drivers across the region to find the right balance between cost and protection. Reach out for a policy review before the next storm season or before your renewal date: a 15-minute conversation could save you thousands.
On this page
Fully licensed
Chabert Insurance: The Ehrhardt Agency is a fully licensed independent insurance agency serving individuals, families, and businesses across Louisiana and Mississippi.
From our offices in Mandeville and New Orleans, we proudly serve clients in Mandeville, Covington, New Orleans, Kenner, Metairie, Harahan, River Ridge, and Slidell, as well as the Westbank and St. Bernard Parish, and communities throughout Louisiana and Mississippi. As an independent agency, our team works with a wide range of top-rated carriers to provide personal and commercial coverage — home, auto, flood, commercial, life, and more — built around the real needs of the people and businesses we protect.
AUTO INSURANCE BY CITY
About the Author
Ryan J. Ehrhardt
Owner / Licensed Agent
I'm Ryan J. Ehrhardt, owner and licensed agent at Chabert Insurance: The Ehrhardt Agency. I lead our team across our Mandeville and New Orleans offices, and I work with families and business owners every day to find coverage that fits their lives. I believe insurance should be simple to understand, so I take the time to explain your options in plain language before you decide.
As an independent agent, I answer to you, not to a single carrier. That means I can shop your policy across many companies and focus on what protects you best. When you call our office, you reach a real person who knows your account. I would be glad to review your coverage and help you feel confident about it.
[CONFIRM name]
Google review · Mandeville office
Home, Auto, Flood, Commercial & Life Insurance
Insurance built around your life in Louisiana
We compare coverage across many carriers and build one program that protects everything you own.
Home Insurance
Cover the cost to rebuild your house, replace your belongings, and answer a liability claim against your household.
Auto Insurance
Protect your vehicles with liability, collision, and uninsured motorist limits that hold up after a serious Louisiana wreck.
Flood Insurance
Your homeowners policy excludes flood. We quote NFIP and private options for your building and its contents.
Commercial Insurance
Liability, property, workers' compensation, and commercial auto for Louisiana businesses, priced against how your company operates.
Life Insurance
Replace the income your family depends on, with term and permanent options priced across several carriers.
Umbrella Insurance
Add a layer of liability protection above your auto and home limits, usually for a modest premium.
Ruston
Baton Rouge
Mandeville
Gretna
Louisiana Home Insurance
Home insurance built around where you live
Home insurance is our specialty. We write homeowners policies across Louisiana and price them against the wind, hail, and flood risk in your parish.
Areas we cover
Commercial Insurance for Louisiana Businesses
Coverage that keeps your business running
We build commercial programs around how your company actually operates, then compare carriers on price and claim service.
General Liability
Covers claims of bodily injury or property damage that come from your day-to-day operations.
Commercial Property
Protects your building, equipment, and inventory against fire, storm, theft, and other covered losses.
Workers' Compensation
Pays medical care and lost wages when an employee is hurt on the job, as Louisiana requires.
Commercial Auto
Covers the vehicles your business owns, along with the employees who drive them for work.
Professional Liability
Covers claims that your professional advice or services caused a client a financial loss.
Cyber Liability
Handles breach response, notification costs, and liability after customer data is exposed.
[CONFIRM name]
Google review · Mandeville office
Business Insurance by Industry
Specialized coverage for your line of work
Every trade carries its own risks. We know the coverage these Louisiana businesses need and where the gaps usually sit.
Plumbers
Liability, tools, and commercial auto coverage built for water damage claims and job-site risk.
Restaurants
Property, liquor liability, and spoilage coverage for kitchens, dining rooms, and your staff.
Real Estate Investors
Landlord property, liability, and vacancy coverage for rentals, flips, and multi-unit buildings.
[CONFIRM name]
Google review · Mandeville office
How to Get Insured in 4 Steps
Getting covered is simple
You talk to a licensed agent from the first call to the annual review.
1
Tell us about you
Share what you want to protect. A licensed agent asks about your home, vehicles, family, or business and gathers the details carriers need.
2
We shop our carriers
We compare options across the markets we represent and look at price, coverage limits, and how each carrier handles claims.
3
Review your choices
We explain coverage and price in plain language, side by side, so you can see the trade-offs before you choose.
4
Get covered
Your policy starts, you get your documents, and we review the coverage with you each year.
5-Star Rated by Louisiana Clients
What our clients say
Louisiana families and business owners rate us 5 stars for clear advice and fast answers.
139+ five-star reviews across our Mandeville and New Orleans offices