Variant Insurance Group is a licensed independent insurance agency in Minnesota. [CONFIRM license #.]
Get a Quote
Variant Insurance Group is a licensed independent insurance agency serving Minnesota families and businesses.
From our office in Maple Plain, our team works with many of Minnesota's top-rated carriers so your home, auto, life, and business coverage fits your real needs. We serve families and businesses across Minnesota.
New title
New title
Lafayette sits at the crossroads of Louisiana's oil and gas corridor, a growing healthcare sector, and a retail scene fueled by Acadiana's unique culture. That mix creates a business environment unlike anywhere else in the state, and it demands insurance coverage built for local realities. A single hurricane season can shutter storefronts for weeks. An oilfield accident can generate six-figure claims overnight. A patient complaint can spiral into a malpractice lawsuit that threatens years of work. If you own or operate a business here, understanding your coverage options isn't optional: it's survival. This guide breaks down what Lafayette business owners need to know about general liability, business income protection, commercial flood insurance, and workers' compensation so you can protect your operation from the risks that actually keep local owners up at night. Whether you're running a wireline company out of Broussard, a clinic on Ambassador Caffery, or a boutique downtown, the right policy mix looks different for each. Louisiana's legal environment has shifted in recent years too, and those changes directly affect what you'll pay and what you need. The goal here is simple: give you the specific, practical information that helps you make smarter decisions about your coverage.
Essential General Liability Needs for Lafayette's Core Industries
General liability insurance is the foundation of nearly every commercial policy in Louisiana. It covers bodily injury, property damage, and personal injury claims made by third parties. But the risks it protects against vary dramatically depending on your industry. A one-size-fits-all approach leaves gaps that can cost you everything.
Lafayette's economy leans heavily on three sectors, and each one faces distinct liability exposures that demand careful attention.
Oilfield Support: Managing High-Risk Operations
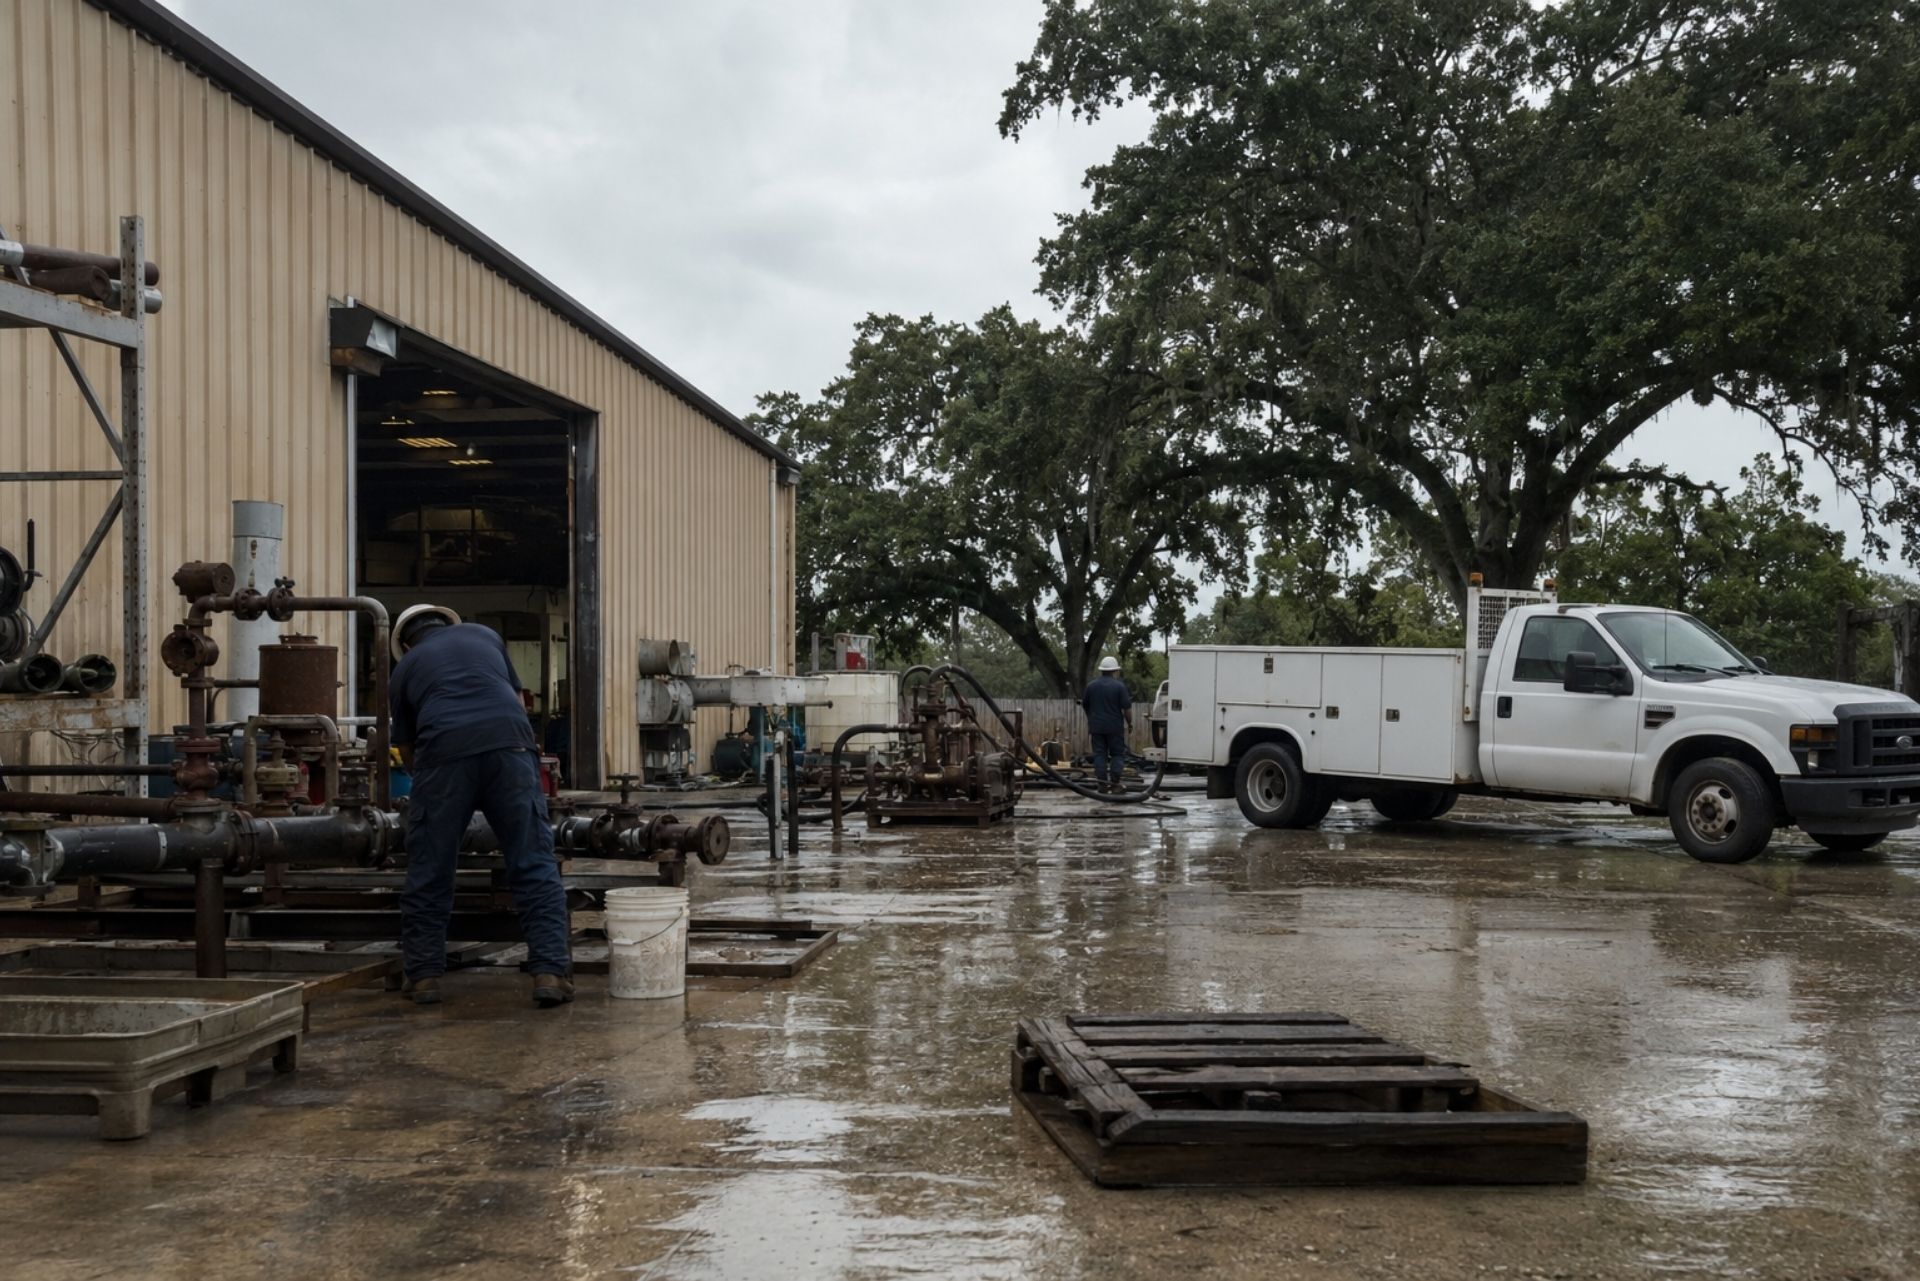
Oilfield support companies, from well service crews to equipment rental firms, operate in one of the most hazardous industries in the country. General liability for these businesses must account for property damage to wellsite equipment, third-party injuries on active job sites, and pollution incidents that can trigger environmental cleanup costs.
One critical factor for Lafayette-area oilfield contractors is Louisiana's oilfield anti-indemnity statute, which restricts certain indemnification clauses in oilfield contracts. This means you can't always shift liability to the operator through your contract language. Your own GL policy has to be strong enough to stand on its own. Many contractors also need umbrella policies with limits of $5 million or more because operators require proof of high coverage before granting site access.
Pollution liability riders are another must-have. Standard GL policies typically exclude pollution events, and a spill on a lease road or wellsite can generate cleanup costs that dwarf the original job's revenue.
Healthcare Providers: Patient Safety and Liability
Lafayette's medical community ranges from large hospital systems to small specialty clinics and home health agencies. General liability for healthcare providers covers slip-and-fall injuries in your waiting room, damage to a patient's personal property, and similar premises-related incidents.
Don't confuse this with professional liability, which covers errors in treatment or diagnosis. You need both. A patient who trips over a loose floor tile files a GL claim. A patient alleging a misdiagnosis files a professional liability claim. These are separate policies with separate limits.
Louisiana recently transitioned to a modified comparative fault system under the 51% Bar Rule, which prevents a plaintiff from recovering any damages if they're found to be 51% or more at fault. This shift affects how liability claims are evaluated and can influence settlement strategies for healthcare providers facing premises liability suits.
Retail and Hospitality: Protecting Physical Locations
Retail shops, restaurants, and hotels in Lafayette face constant foot traffic, and that traffic brings constant exposure. A customer slipping on a wet floor at a Cajun restaurant, a child injured by a display at a boutique, or a guest's car damaged in your parking lot: these are everyday GL scenarios.
Your policy should include products-completed operations coverage if you sell goods or serve food. If a customer gets sick from a dish or a product malfunctions after purchase, this extension covers the resulting claims. Many small retailers carry minimum GL limits of $1 million per occurrence, but businesses with higher foot traffic or alcohol service should consider $2 million or more.
Comparing General Liability and Professional Liability
These two coverage types get confused constantly, but they protect against fundamentally different risks. Getting this wrong means you could pay premiums for years and still have no coverage when a claim hits.
Coverage Comparison Table
| Feature | General Liability | Professional Liability |
|---|---|---|
| What it covers | Bodily injury, property damage, personal injury to third parties | Errors, omissions, or negligence in professional services |
| Who needs it | Nearly every business | Service-based businesses: consultants, healthcare, engineers, accountants |
| Typical trigger | Customer slips in your store | Client alleges your advice caused financial loss |
| Coverage basis | Usually occurrence-based | Often claims-made (only covers claims filed during policy period) |
| Average cost range | $500 - $3,000/year for small businesses | $1,000 - $5,000+/year depending on profession |
| Required by law? | Not in Louisiana, but often required by contracts/landlords | Required for some licensed professions |
If you're an oilfield consultant, a physical therapist, or an IT firm, you likely need both. A local agency like Chabert Insurance can help you identify where your specific gaps are and build a package that addresses both premises and professional exposures.
Protecting Cash Flow with Business Income Coverage
Most Lafayette business owners insure their buildings and equipment but forget about the income those assets generate. Business income coverage, sometimes called business interruption insurance, replaces your lost revenue when a covered event forces you to close temporarily.
Think about it this way: your property policy pays to rebuild your damaged storefront. Your business income policy pays your rent, payroll, and loan payments while you wait for the rebuild to finish.
Covering Fixed Expenses During Repairs
The bills don't stop when your doors close. Lease payments, employee salaries, loan obligations, and utility minimums keep coming whether you're open or not. Business income coverage steps in to cover these fixed costs, plus the net profit you would have earned during the closure.
This is especially relevant in Lafayette, where hurricane damage can take months to repair. A restaurant forced to close for 90 days after a storm could lose $150,000 or more in revenue. Without business income coverage, that loss comes straight out of your pocket.
The risk management implications of recent Louisiana legislative changes also affect how quickly claims get processed and paid, making it even more important to carry adequate limits.
Understanding the 'Period of Restoration'
Your business income policy doesn't pay indefinitely. It covers the "period of restoration," which starts when the damage occurs and ends when your property should be repaired with reasonable speed. The key word is "should." If your contractor drags out the timeline, your insurer might stop paying based on what a reasonable repair schedule would look like.
You can purchase an extended period of indemnity endorsement that continues coverage for 30, 60, or even 365 days after you reopen. This accounts for the reality that customers don't come flooding back the moment you unlock the doors. Revenue ramps up gradually, and this endorsement bridges that gap.
Navigating Commercial Flood Insurance in Acadiana
Lafayette Parish sits in a region where flooding isn't a question of if but when. The 2016 floods devastated businesses across Acadiana, and storm surge, heavy rainfall, and poor drainage continue to pose threats every hurricane season.
Why Standard Policies Exclude Flood Damage
Your commercial property policy almost certainly excludes flood damage. This surprises many business owners who assume their "all-risk" policy covers everything. It doesn't. Flood is a named exclusion in virtually every standard commercial property form in the United States.
This means that if rising water damages your inventory, equipment, or building, your property insurer won't pay a dime unless you carry a separate flood policy. The distinction between "flood" (rising water from external sources) and "water damage" (a burst pipe inside your building) matters enormously in claims. Many Lafayette businesses learned this the hard way during past flood events.
Private Flood vs. NFIP Options
You have two main paths for commercial flood coverage. The National Flood Insurance Program offers policies with maximum commercial building limits of $500,000 and contents limits of $500,000. For many Lafayette businesses, especially those with significant equipment or inventory, those caps aren't enough.
Private flood insurers have expanded significantly in Louisiana and often provide higher limits, broader coverage terms, and sometimes lower premiums than NFIP policies. Recent legislative activity in Louisiana's 2026 session has addressed flood insurance market reforms that could affect pricing and availability for commercial policyholders.
Working with a knowledgeable local agency like Chabert Insurance helps you compare NFIP and private options side by side. The right choice depends on your property's flood zone, your building's value, and how much inventory or equipment you keep on-site. Louisiana's flood insurance regulatory framework continues to evolve, so staying current matters.
Frequently Asked Questions About Lafayette Business Insurance
Common Coverage Queries
Do I need workers' compensation if I only have a few employees? Louisiana requires workers' comp for any business with one or more employees. Independent contractors are generally exempt, but misclassifying workers as contractors can result in fines and denied claims.
Can I bundle general liability with property insurance? Yes. A Business Owners Policy, or BOP, bundles GL, property, and business income coverage into a single policy, often at a lower cost than buying each separately. Most small to mid-size Lafayette businesses qualify.
How much general liability coverage do I need? Most small businesses carry $1 million per occurrence and $2 million aggregate. Oilfield contractors and healthcare providers often need higher limits or umbrella policies to meet contract or regulatory requirements.
Does my landlord's insurance cover my business? No. Your landlord's policy covers the building structure. Your inventory, equipment, fixtures, and liability exposure are your responsibility. You need your own commercial policy.
Is flood insurance required for my business? If you have a federally backed mortgage or SBA loan on a property in a high-risk flood zone, yes. Even if it's not required, carrying flood coverage in Acadiana is strongly recommended given the region's history.
What's the difference between claims-made and occurrence policies? An occurrence policy covers incidents that happen during the policy period, regardless of when the claim is filed. A claims-made policy only covers claims filed while the policy is active. This distinction matters most for professional liability.
Making the Right Choice for Your Local Business
Getting business insurance right in Lafayette means understanding how your specific industry, location, and operations create unique exposures. An oilfield support company and a retail boutique might sit on the same street, but their risk profiles couldn't be more different.
The smartest move is to work with an agency that understands Louisiana's insurance market from the inside. Chabert Insurance: The Ehrhardt Agency specializes in helping Acadiana businesses build coverage packages that fit their actual risks, not generic templates. From general liability and workers' compensation to commercial flood and business income protection, the right combination keeps your doors open when the unexpected hits.
Don't wait for a claim to find out what your policy doesn't cover. Review your coverage annually, especially before hurricane season, and make sure your limits still match your revenue and asset values. Your business is worth protecting properly.
On this page
Fully licensed
Chabert Insurance: The Ehrhardt Agency is a fully licensed independent insurance agency serving individuals, families, and businesses across Louisiana and Mississippi.
From our offices in Mandeville and New Orleans, we proudly serve clients in Mandeville, Covington, New Orleans, Kenner, Metairie, Harahan, River Ridge, and Slidell, as well as the Westbank and St. Bernard Parish, and communities throughout Louisiana and Mississippi. As an independent agency, our team works with a wide range of top-rated carriers to provide personal and commercial coverage — home, auto, flood, commercial, life, and more — built around the real needs of the people and businesses we protect.
INSURANCE COVERAGE
BUSINESS INSURANCE BY CITY
OTHER INSURANCE COVERAGE
About the Author
Ryan J. Ehrhardt
Owner / Licensed Agent
I'm Ryan J. Ehrhardt, owner and licensed agent at Chabert Insurance: The Ehrhardt Agency. I lead our team across our Mandeville and New Orleans offices, and I work with families and business owners every day to find coverage that fits their lives. I believe insurance should be simple to understand, so I take the time to explain your options in plain language before you decide.
As an independent agent, I answer to you, not to a single carrier. That means I can shop your policy across many companies and focus on what protects you best. When you call our office, you reach a real person who knows your account. I would be glad to review your coverage and help you feel confident about it.
[CONFIRM name]
Google review · Mandeville office
Home, Auto, Flood, Commercial & Life Insurance
Insurance built around your life in Louisiana
We compare coverage across many carriers and build one program that protects everything you own.
Home Insurance
Cover the cost to rebuild your house, replace your belongings, and answer a liability claim against your household.
Auto Insurance
Protect your vehicles with liability, collision, and uninsured motorist limits that hold up after a serious Louisiana wreck.
Flood Insurance
Your homeowners policy excludes flood. We quote NFIP and private options for your building and its contents.
Commercial Insurance
Liability, property, workers' compensation, and commercial auto for Louisiana businesses, priced against how your company operates.
Life Insurance
Replace the income your family depends on, with term and permanent options priced across several carriers.
Umbrella Insurance
Add a layer of liability protection above your auto and home limits, usually for a modest premium.
Ruston
Baton Rouge
Mandeville
Gretna
Louisiana Home Insurance
Home insurance built around where you live
Home insurance is our specialty. We write homeowners policies across Louisiana and price them against the wind, hail, and flood risk in your parish.
Areas we cover
Commercial Insurance for Louisiana Businesses
Coverage that keeps your business running
We build commercial programs around how your company actually operates, then compare carriers on price and claim service.
General Liability
Covers claims of bodily injury or property damage that come from your day-to-day operations.
Commercial Property
Protects your building, equipment, and inventory against fire, storm, theft, and other covered losses.
Workers' Compensation
Pays medical care and lost wages when an employee is hurt on the job, as Louisiana requires.
Commercial Auto
Covers the vehicles your business owns, along with the employees who drive them for work.
Professional Liability
Covers claims that your professional advice or services caused a client a financial loss.
Cyber Liability
Handles breach response, notification costs, and liability after customer data is exposed.
[CONFIRM name]
Google review · Mandeville office
Business Insurance by Industry
Specialized coverage for your line of work
Every trade carries its own risks. We know the coverage these Louisiana businesses need and where the gaps usually sit.
Plumbers
Liability, tools, and commercial auto coverage built for water damage claims and job-site risk.
Restaurants
Property, liquor liability, and spoilage coverage for kitchens, dining rooms, and your staff.
Real Estate Investors
Landlord property, liability, and vacancy coverage for rentals, flips, and multi-unit buildings.
[CONFIRM name]
Google review · Mandeville office
How to Get Insured in 4 Steps
Getting covered is simple
You talk to a licensed agent from the first call to the annual review.
1
Tell us about you
Share what you want to protect. A licensed agent asks about your home, vehicles, family, or business and gathers the details carriers need.
2
We shop our carriers
We compare options across the markets we represent and look at price, coverage limits, and how each carrier handles claims.
3
Review your choices
We explain coverage and price in plain language, side by side, so you can see the trade-offs before you choose.
4
Get covered
Your policy starts, you get your documents, and we review the coverage with you each year.
5-Star Rated by Louisiana Clients
What our clients say
Louisiana families and business owners rate us 5 stars for clear advice and fast answers.
139+ five-star reviews across our Mandeville and New Orleans offices