Variant Insurance Group is a licensed independent insurance agency in Minnesota. [CONFIRM license #.]
Get a Quote
Variant Insurance Group is a licensed independent insurance agency serving Minnesota families and businesses.
From our office in Maple Plain, our team works with many of Minnesota's top-rated carriers so your home, auto, life, and business coverage fits your real needs. We serve families and businesses across Minnesota.
Louisiana demolition contractors face a set of risks that few other trades encounter. Between hurricane season bringing waves of teardown work, aging structures loaded with hazardous materials, and the constant threat of damaging neighboring properties, the insurance needs of a demolition crew go far beyond a standard general liability policy. Getting the right coverage isn't just about checking a regulatory box: it's about keeping your business solvent when a wall falls the wrong way or a buried fuel tank ruptures during excavation.
If you run a demolition operation in New Orleans, Mandeville, or anywhere along the Gulf Coast, your exposure profile is shaped by Louisiana's weather, its building stock, and its legal environment. The state's modified comparative fault system means you can still face significant liability even if you're only partially at fault for an incident. Understanding what your policy actually covers, and where the gaps hide, is the difference between surviving a claim and shutting your doors.
This guide breaks down the specific insurance concerns Louisiana demolition contractors need to understand: post-storm recovery work, collapse and underground hazards, pollution liability, and claims from adjacent property damage.
Navigating Louisiana's Unique Demolition Risks
Louisiana's demolition industry operates in a climate unlike any other state. The combination of frequent hurricanes, flood-prone terrain, and dense urban neighborhoods in cities like New Orleans creates a risk environment where standard contractor policies regularly fall short.
Your exposure doesn't just come from the structure you're tearing down. It comes from what's inside those walls, what's buried beneath the slab, and who's living or working next door. A demolition contractor here needs to think about wind-damaged buildings that are structurally compromised before you even touch them, soil conditions that shift unpredictably, and municipal codes that carry real enforcement teeth.
Post-Storm Teardowns and Hurricane Recovery Hazards
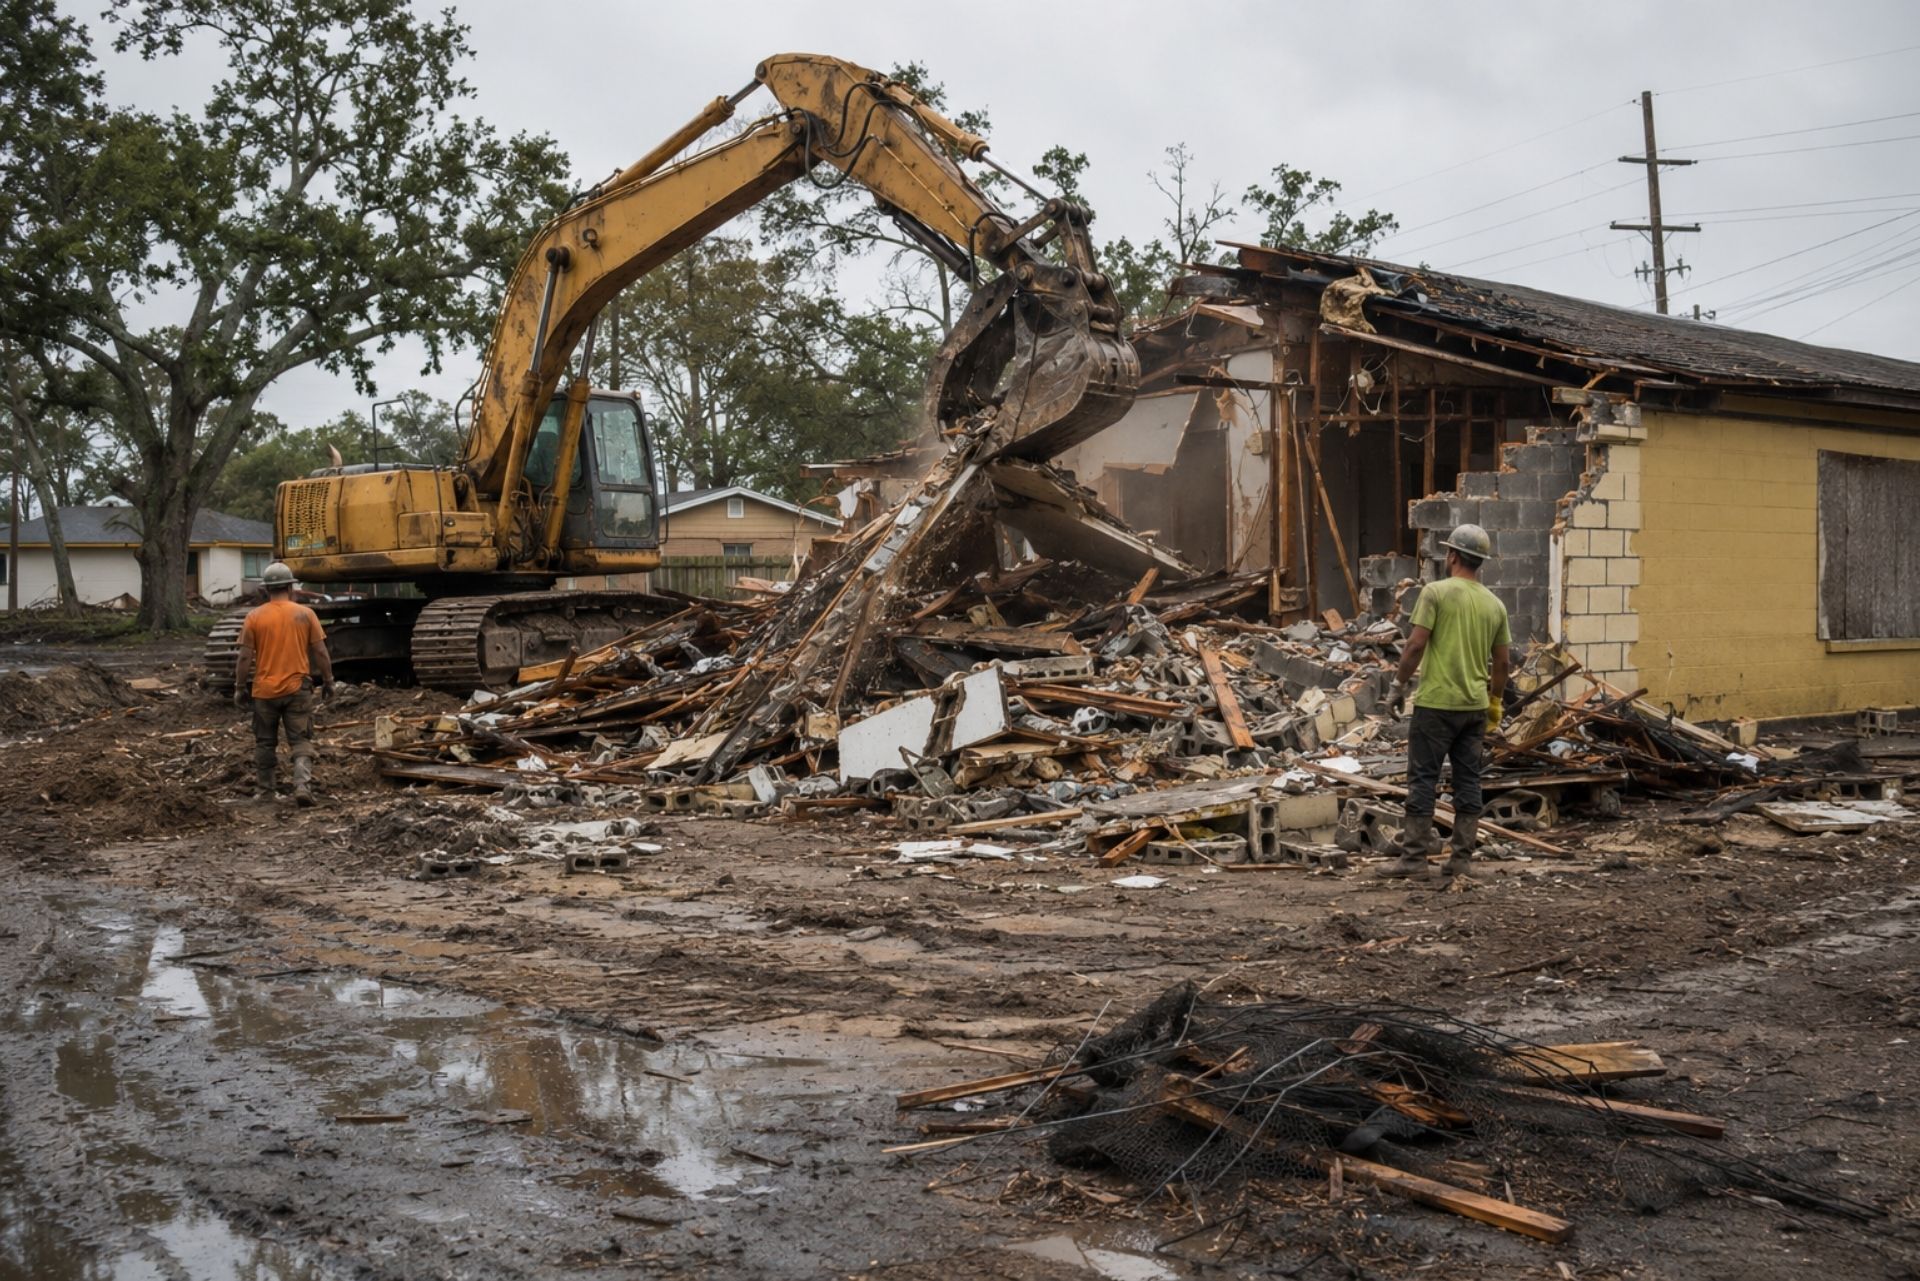
After a major hurricane, demolition contractors are in high demand. That urgency creates risk. Storm-damaged buildings are unpredictable: load-bearing walls may have shifted, water intrusion can weaken foundations, and debris fields often conceal hazards like downed power lines or ruptured gas connections.
Post-storm teardown work also brings heightened regulatory scrutiny. FEMA-funded projects carry their own insurance and documentation requirements. If you're working on a structure with a National Flood Insurance Program claim, your liability exposure increases because federal dollars are involved.
One practical concern many contractors overlook: your existing policy may have exclusions for work on structures already declared condemned or structurally unsound. If a building has been red-tagged by the city, some insurers consider it an uninsurable risk under your standard terms. You'll want to confirm your policy language before accepting that job.
State Licensing and Insurance Minimums
Louisiana's licensing board has been tightening requirements. Effective August 1, 2026, Act 757 raised the minimum general liability insurance requirement for residential demolition and home improvement contractors from $100,000 to $300,000 per occurrence. That's a significant jump, and contractors who haven't updated their policies risk losing their license.
The Louisiana State Licensing Board for Contractors (LSLBC) now also requires proof of workers' compensation coverage before issuing or renewing a license. If you're running a crew of any size, this isn't optional. The 2026 LSLBC overhaul introduced stricter enforcement mechanisms, including the ability to suspend licenses for lapses in coverage.
Critical Coverage for Structural and Site Hazards
The physical act of demolition carries inherent danger, and your insurance needs to reflect the specific ways things go wrong on a teardown job. Two categories of risk stand out: collapse and underground exposures (known in the industry as XCU), and damage to adjacent properties.
Managing Collapse and Underground (XCU) Exposures
XCU stands for explosion, collapse, and underground hazards. Many standard general liability policies exclude all three. If your policy has an XCU exclusion, you essentially have no coverage for the most likely claims a demolition contractor will face.
Collapse exposure is straightforward: you're literally bringing buildings down. If an uncontrolled collapse injures a worker, damages a neighboring structure, or sends debris into a public roadway, you need a policy that explicitly covers collapse-related claims.
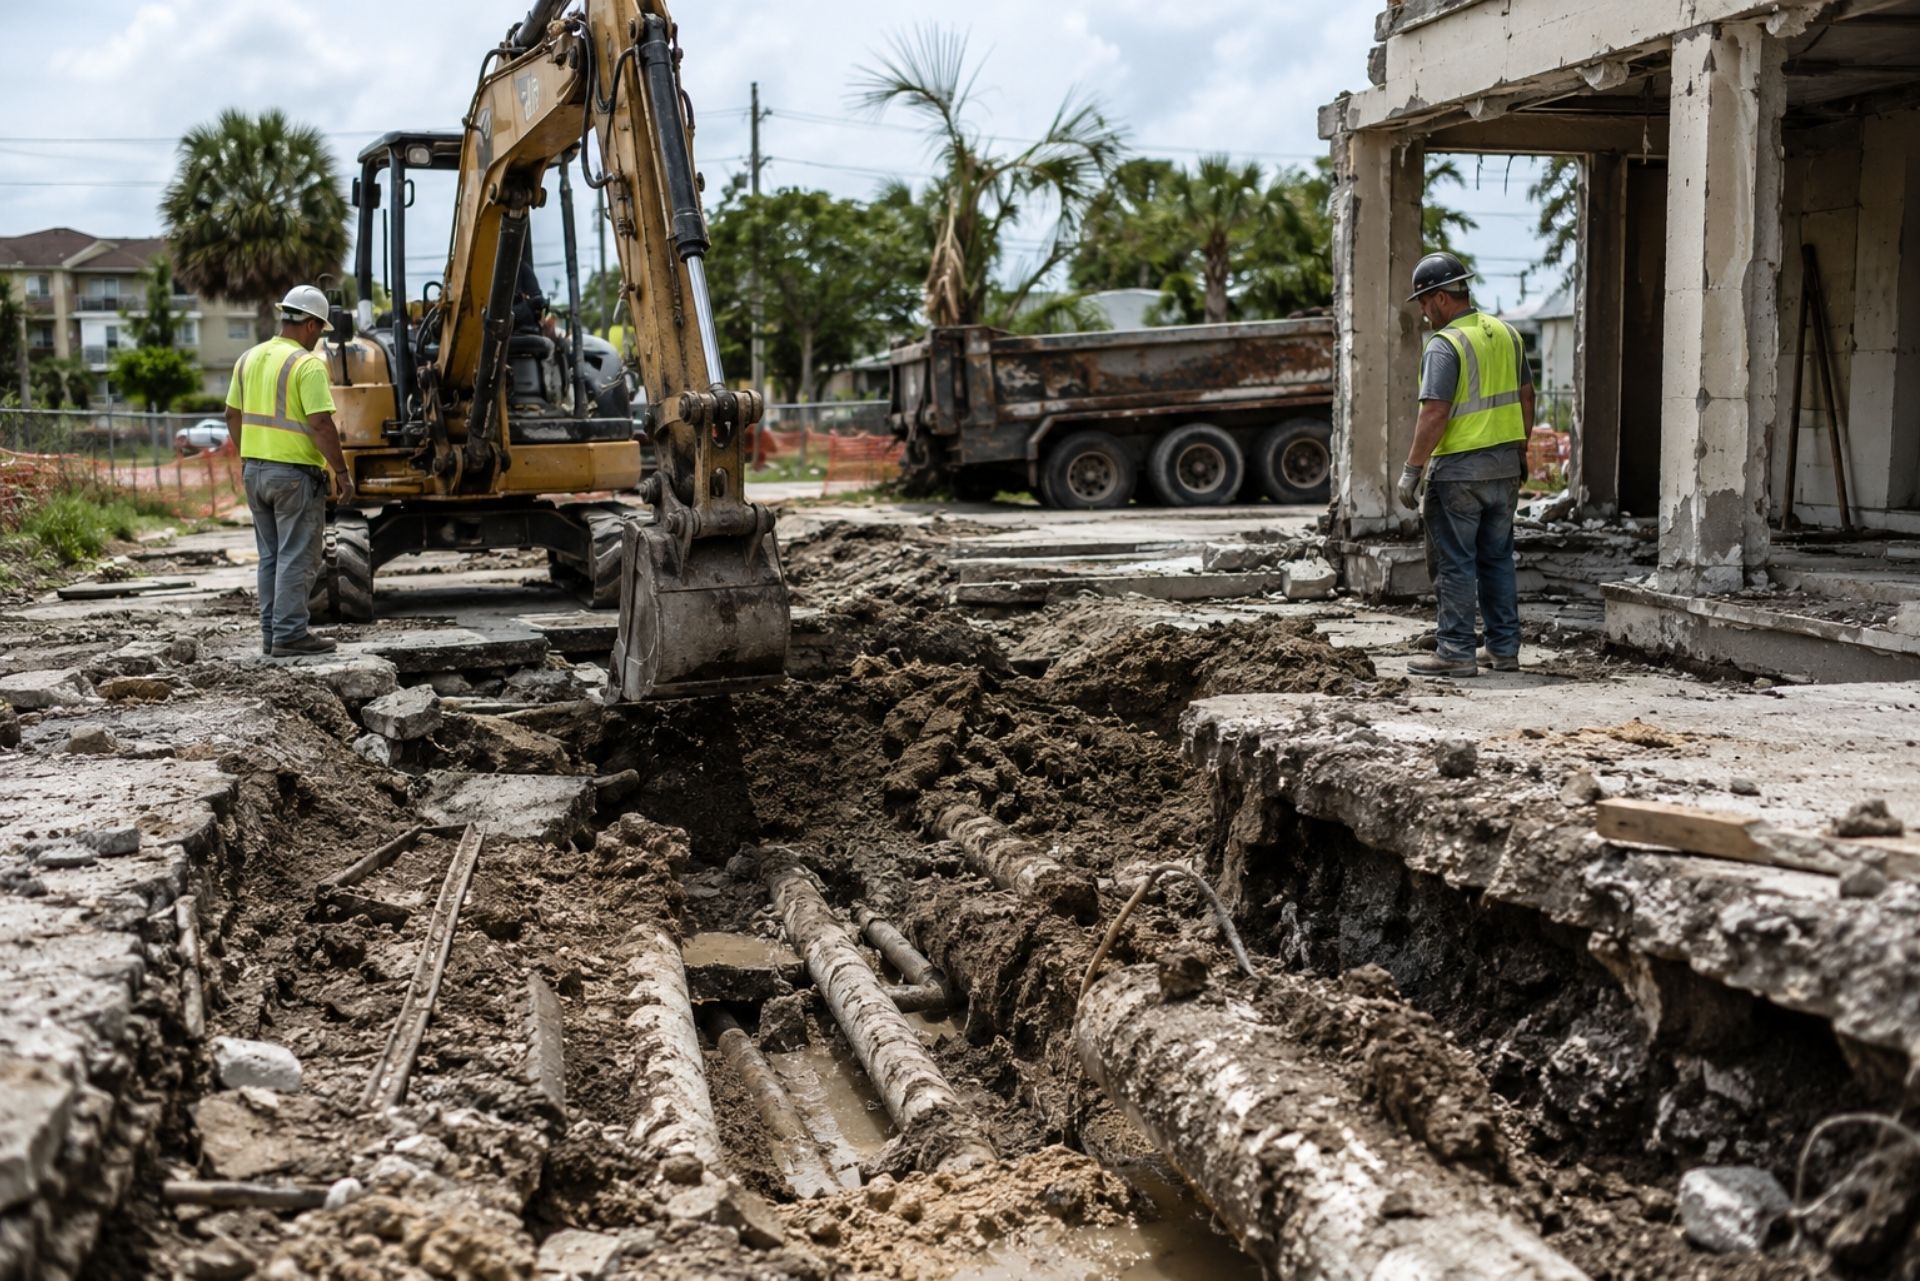
Underground exposure matters because Louisiana's soil is full of buried infrastructure. Gas lines, water mains, fiber optic cables, and old fuel tanks are common on urban demolition sites. Louisiana's updated dig laws, signed by Governor Landry through SB469, impose stricter requirements for utility notification before excavation. You're required to contact Louisiana 811 before any ground-disturbing work. Failing to do so doesn't just risk a fine: it can void your insurance coverage entirely if you hit a utility line.
Protecting Adjacent Properties and Shared Walls
In New Orleans, many demolition jobs involve shotgun doubles, row houses, or commercial buildings that share party walls with occupied structures. Removing one side of a shared wall without proper shoring can cause the neighbor's building to crack, shift, or partially collapse.
The $106 million settlement in the Hard Rock Hotel collapse case is a stark reminder of what structural failures can cost in this city. While that was a construction project rather than a demolition job, the liability principles are identical. If your work causes damage to a neighboring property, you're on the hook.
Your general liability policy should include completed operations coverage and should not exclude damage to property in your care, custody, or control. A local agency like Chabert Insurance: The Ehrhardt Agency can review your policy for these specific exclusions, which are common in off-the-shelf contractor policies.
Addressing Pollution Liability and Hazardous Materials
Pollution is one of the most underinsured risks in demolition. Standard general liability policies almost universally exclude pollution-related claims, yet demolition contractors encounter hazardous materials on nearly every job involving pre-1980 construction.
Asbestos, Lead, and Mold During Post-Storm Cleanup
Older Louisiana buildings are loaded with asbestos in floor tiles, pipe insulation, and roofing materials. Lead paint is present in most pre-1978 structures. After a hurricane, standing water creates mold colonies that can become a health hazard during demolition.
If your crew disturbs asbestos without proper abatement procedures, you face both EPA enforcement action and personal injury claims from workers or nearby residents. These claims can take years to surface: mesothelioma has a latency period of 20 to 50 years. Your policy needs to account for long-tail liability, not just immediate incidents.
A standalone Contractor's Pollution Liability (CPL) policy is the standard solution. It covers both first-party cleanup costs and third-party bodily injury or property damage claims arising from the release of pollutants during your work.
Sudden vs. Gradual Pollution Events
Insurance policies draw a sharp line between sudden and gradual pollution events, and the distinction matters for your claim outcome.
A sudden event might be a backhoe puncturing an underground diesel tank, causing an immediate spill. Most CPL policies cover this. A gradual event could be contaminated runoff from a demolition site seeping into a neighbor's property over weeks or months. Coverage for gradual events is harder to find and more expensive, but it's essential for sites with known contamination.
The 2026 construction insurance market has seen capacity tighten for pollution coverage, particularly in coastal states. If you're shopping for a CPL policy, expect underwriters to ask detailed questions about your site assessment procedures, subcontractor management, and hazardous materials protocols.
Comparison of Standard vs. Specialized Demolition Policies
| Coverage Feature | Standard GL Policy | Specialized Demolition Policy |
|---|---|---|
| XCU Coverage | Usually excluded | Included |
| Pollution Liability | Excluded | Available as endorsement or standalone |
| Adjacent Property Damage | Limited or excluded | Covered with proper limits |
| Completed Operations | Often limited | Extended tail available |
| Post-Storm/Condemned Structures | May be excluded | Covered with documentation |
| Underground Utility Damage | Excluded if 811 not called | Covered with compliance verification |
| Typical Annual Premium | $3,000-$8,000 | $12,000-$35,000+ |
The price difference is real, but so is the gap in protection. A single adjacent property damage claim can easily exceed $500,000. Working with an agency that understands demolition-specific risks, like the team at Chabert Insurance: The Ehrhardt Agency in New Orleans and Mandeville, helps you build a policy package that matches your actual exposure rather than a generic contractor template.
Common Questions About Louisiana Demolition Insurance
Do I need a separate pollution policy, or can I add it to my GL? Most general liability policies exclude pollution entirely. You'll typically need a standalone Contractor's Pollution Liability policy, though some specialized demolition programs offer it as an endorsement.
What happens if I damage a utility line during demolition? If you failed to call Louisiana 811 before digging, your insurer can deny the claim. Compliance with the state's dig notification law is a condition of coverage for most policies.
Does my workers' comp cover asbestos exposure claims filed years later? Louisiana workers' compensation does cover occupational disease claims, but the statute of limitations and prescriptive periods can be complex. The state's personal injury framework applies specific rules to long-latency disease claims.
Are subcontractors covered under my policy? Generally, no. You should require certificates of insurance from every subcontractor and verify their coverage includes XCU and pollution liability. If they're uninsured, the claim rolls uphill to you.
How much liability coverage do I actually need? The state minimum is $300,000 per occurrence as of August 2026, but most commercial demolition contracts require $1 million to $2 million. Government contracts often require even higher limits.
Can I get coverage for work on condemned buildings? Yes, but not from every carrier. You'll need a specialized program that underwrites demolition-specific risks and understands post-storm teardown work.
Protecting Your Business Before the Next Storm
Hurricane season doesn't wait for your policy renewal date. The time to review your demolition insurance coverage is before the storm hits, not while you're fielding calls from property owners desperate for teardown crews.
Start by pulling your current policy and checking for XCU exclusions, pollution carve-outs, and limitations on adjacent property damage. If you find gaps, and most standard policies have them, talk to an agency with real experience in Louisiana's demolition market. Chabert Insurance: The Ehrhardt Agency works with contractors across the New Orleans and Mandeville areas to build coverage packages that account for the specific hazards of Gulf Coast demolition work.
Your insurance should be as solid as the structures you're taking down. Get it reviewed now, and you'll be ready to work confidently when the next storm rolls through.
On this page
Fully licensed
Chabert Insurance: The Ehrhardt Agency is a fully licensed independent insurance agency serving individuals, families, and businesses across Louisiana and Mississippi.
From our offices in Mandeville and New Orleans, we proudly serve clients in Mandeville, Covington, New Orleans, Kenner, Metairie, Harahan, River Ridge, and Slidell, as well as the Westbank and St. Bernard Parish, and communities throughout Louisiana and Mississippi. As an independent agency, our team works with a wide range of top-rated carriers to provide personal and commercial coverage — home, auto, flood, commercial, life, and more — built around the real needs of the people and businesses we protect.
OTHER INSURANCE COVERAGE
About the Author
Ryan J. Ehrhardt
Owner / Licensed Agent
I'm Ryan J. Ehrhardt, owner and licensed agent at Chabert Insurance: The Ehrhardt Agency. I lead our team across our Mandeville and New Orleans offices, and I work with families and business owners every day to find coverage that fits their lives. I believe insurance should be simple to understand, so I take the time to explain your options in plain language before you decide.
As an independent agent, I answer to you, not to a single carrier. That means I can shop your policy across many companies and focus on what protects you best. When you call our office, you reach a real person who knows your account. I would be glad to review your coverage and help you feel confident about it.
[CONFIRM name]
Google review · Mandeville office
Home, Auto, Flood, Commercial & Life Insurance
Insurance built around your life in Louisiana
We compare coverage across many carriers and build one program that protects everything you own.
Home Insurance
Cover the cost to rebuild your house, replace your belongings, and answer a liability claim against your household.
Auto Insurance
Protect your vehicles with liability, collision, and uninsured motorist limits that hold up after a serious Louisiana wreck.
Flood Insurance
Your homeowners policy excludes flood. We quote NFIP and private options for your building and its contents.
Commercial Insurance
Liability, property, workers' compensation, and commercial auto for Louisiana businesses, priced against how your company operates.
Life Insurance
Replace the income your family depends on, with term and permanent options priced across several carriers.
Umbrella Insurance
Add a layer of liability protection above your auto and home limits, usually for a modest premium.
Ruston
Baton Rouge
Mandeville
Gretna
Louisiana Home Insurance
Home insurance built around where you live
Home insurance is our specialty. We write homeowners policies across Louisiana and price them against the wind, hail, and flood risk in your parish.
Areas we cover
Commercial Insurance for Louisiana Businesses
Coverage that keeps your business running
We build commercial programs around how your company actually operates, then compare carriers on price and claim service.
General Liability
Covers claims of bodily injury or property damage that come from your day-to-day operations.
Commercial Property
Protects your building, equipment, and inventory against fire, storm, theft, and other covered losses.
Workers' Compensation
Pays medical care and lost wages when an employee is hurt on the job, as Louisiana requires.
Commercial Auto
Covers the vehicles your business owns, along with the employees who drive them for work.
Professional Liability
Covers claims that your professional advice or services caused a client a financial loss.
Cyber Liability
Handles breach response, notification costs, and liability after customer data is exposed.
[CONFIRM name]
Google review · Mandeville office
Business Insurance by Industry
Specialized coverage for your line of work
Every trade carries its own risks. We know the coverage these Louisiana businesses need and where the gaps usually sit.
Plumbers
Liability, tools, and commercial auto coverage built for water damage claims and job-site risk.
Restaurants
Property, liquor liability, and spoilage coverage for kitchens, dining rooms, and your staff.
Real Estate Investors
Landlord property, liability, and vacancy coverage for rentals, flips, and multi-unit buildings.
[CONFIRM name]
Google review · Mandeville office
How to Get Insured in 4 Steps
Getting covered is simple
You talk to a licensed agent from the first call to the annual review.
1
Tell us about you
Share what you want to protect. A licensed agent asks about your home, vehicles, family, or business and gathers the details carriers need.
2
We shop our carriers
We compare options across the markets we represent and look at price, coverage limits, and how each carrier handles claims.
3
Review your choices
We explain coverage and price in plain language, side by side, so you can see the trade-offs before you choose.
4
Get covered
Your policy starts, you get your documents, and we review the coverage with you each year.
5-Star Rated by Louisiana Clients
What our clients say
Louisiana families and business owners rate us 5 stars for clear advice and fast answers.
139+ five-star reviews across our Mandeville and New Orleans offices