Variant Insurance Group is a licensed independent insurance agency in Minnesota. [CONFIRM license #.]
Get a Quote
Variant Insurance Group is a licensed independent insurance agency serving Minnesota families and businesses.
From our office in Maple Plain, our team works with many of Minnesota's top-rated carriers so your home, auto, life, and business coverage fits your real needs. We serve families and businesses across Minnesota.
New title
New title
Louisiana's insurance market has always been shaped by wind, water, and unpredictability. If you own rental properties or flip houses anywhere from New Orleans to Mandeville, your insurance needs are fundamentally different from an investor in, say, Ohio. Percentage-based wind deductibles, mandatory flood considerations, vacancy clauses that can void your coverage mid-renovation: these aren't abstract risks. They're the realities that determine whether a single hurricane season wipes out years of portfolio growth or simply triggers a manageable claim. The good news? Commercial real estate insurance rates in Louisiana have decreased by roughly 30% on average in early 2026, driven by lower reinsurance costs. That shift has created a window for investors to reassess their coverage, lock in better pricing, and close gaps that may have been too expensive to address even two years ago. But cheaper premiums don't help if you're buying the wrong policy. Understanding how Louisiana-specific perils interact with investor-grade coverage types is what separates protected portfolios from exposed ones. This guide breaks down the coverage structures, policy types, and strategic decisions that matter most for Louisiana real estate investors right now.
Navigating the Louisiana Property Insurance Landscape
Louisiana's property insurance market has stabilized considerably since the turbulent years following Hurricanes Laura, Delta, and Ida. The state's homeowners insurance market has shown real signs of recovery, with new carriers entering and existing ones expanding their appetite. That said, investors face a different set of challenges than standard homeowners. Rental properties, especially those held in LLCs, often don't qualify for standard homeowner policies and require dwelling fire or commercial property forms instead.
The Impact of Hurricane Risk on Coastal and Inland Premiums
Coastal parishes like Jefferson, Plaquemines, and St. Tammany carry significantly higher wind premiums than inland areas. But don't assume distance from the coast means low risk. Baton Rouge and Hammond saw major wind and flood damage from recent storms, and insurers price accordingly. Your premium is driven by construction type, roof age, distance to coast, and elevation: not just your ZIP code. A 20-year-old roof in Slidell might cost three times more to insure than a new-construction property in Covington, even though they're only 30 miles apart.
Louisiana Citizens and the Surplus Lines Market
Louisiana Citizens Property Insurance Corporation serves as the insurer of last resort, but it's not designed for investors with large portfolios. Coverage limits are capped, and multi-property investors often get pushed into the surplus lines market. Surplus lines carriers aren't bound by the same rate regulations as admitted carriers, which means premiums can vary wildly. Working with a local agency like Chabert Insurance: The Ehrhardt Agency that understands both the admitted and surplus markets can help you find competitive options without sacrificing coverage quality.
Protecting Buy-and-Hold Portfolios: Wind, Hail, and Flood
Long-term rental investors in Louisiana need to think about three distinct peril categories: wind/hail, flood, and everything else. Each one has its own deductible structure, policy form, and pricing model. Treating them as a single bucket is a common mistake that leads to painful surprises at claim time.
Separating Wind/Hail Deductibles from All Other Perils (AOP)
Most Louisiana property policies split deductibles into two tiers. Your AOP deductible might be $2,500 flat, but your wind/hail deductible is typically 2% to 5% of the dwelling coverage amount. On a property insured for $300,000, a 5% wind deductible means you're covering the first $15,000 out of pocket. That's a significant self-insured retention, and many investors don't realize it until they file a claim. Choosing a lower wind deductible percentage will raise your premium, but the math often favors it on higher-value properties.
Flood Insurance: NFIP vs. Private Market Options
The National Flood Insurance Program caps coverage at $250,000 for residential buildings, which may not be enough for larger multi-family investments. Private flood insurance has expanded rapidly in Louisiana and can offer higher limits, broader coverage, and sometimes lower premiums for properties outside high-risk zones. Landlord insurance policies in Louisiana often don't include flood coverage by default, so you'll need a separate policy regardless of which route you choose.
Actual Cash Value vs. Replacement Cost Value in Storm Zones
A critical policy detail for Louisiana investors is whether your dwelling coverage pays actual cash value (ACV) or replacement cost value (RCV). ACV deducts depreciation, meaning a 15-year-old roof destroyed by a hurricane might only pay out a fraction of what it costs to replace. RCV pays the full replacement cost. Louisiana's 2024 legislative changes under Act 480 introduced stated value insurance policies that allow property owners to insure for loan value rather than full replacement cost, which can lower premiums. But investors need to weigh the premium savings against the risk of being underinsured after a major storm.
Coverage Comparison: DP-1 vs. DP-3 Policies
Investor dwelling policies come in two primary forms, and the difference between them is substantial.
| Feature | DP-1 (Basic Form) | DP-3 (Special Form) |
|---|---|---|
| Covered Perils | Named perils only (fire, lightning, etc.) | Open perils (all risks unless excluded) |
| Wind/Hail | May require separate endorsement | Typically included |
| Water Damage | Very limited | Broader coverage for sudden/accidental |
| Theft | Not covered | Covered |
| Loss of Rents | Usually not included | Often included or available |
| Cost | Lower premium | Higher premium |
| Best For | Low-value properties, tight budgets | Properties you can't afford to lose |
DP-1 policies are bare-bones. They cover a short list of named perils and pay on an ACV basis. DP-3 policies cover everything that isn't specifically excluded, which means you're protected against unexpected events you didn't anticipate. For most Louisiana rental investors, DP-3 is the better choice, especially in a market where storms can cause damage from sources you'd never list on a named-perils form.
Fix-and-Flip Coverage: Builders Risk and Vacancy Requirements
Flipping houses in Louisiana introduces two coverage challenges that trip up even experienced investors: vacancy restrictions and the need for builders risk during major renovations. Standard dwelling policies weren't designed for properties under active construction or sitting empty between tenants.
The 30-Day Vacancy Clause Trap
Most dwelling and commercial property policies include a vacancy clause that kicks in after 30 to 60 days of the property being unoccupied. Once triggered, the insurer can reduce claim payouts by 15% or deny certain perils entirely, including vandalism and water damage. If you're between tenants or staging a property for sale, this clause can quietly void the coverage you're counting on. Some investors don't discover this until they file a claim for burst pipes in an empty property and get a fraction of what they expected.
Builders Risk for Major Structural Renovations
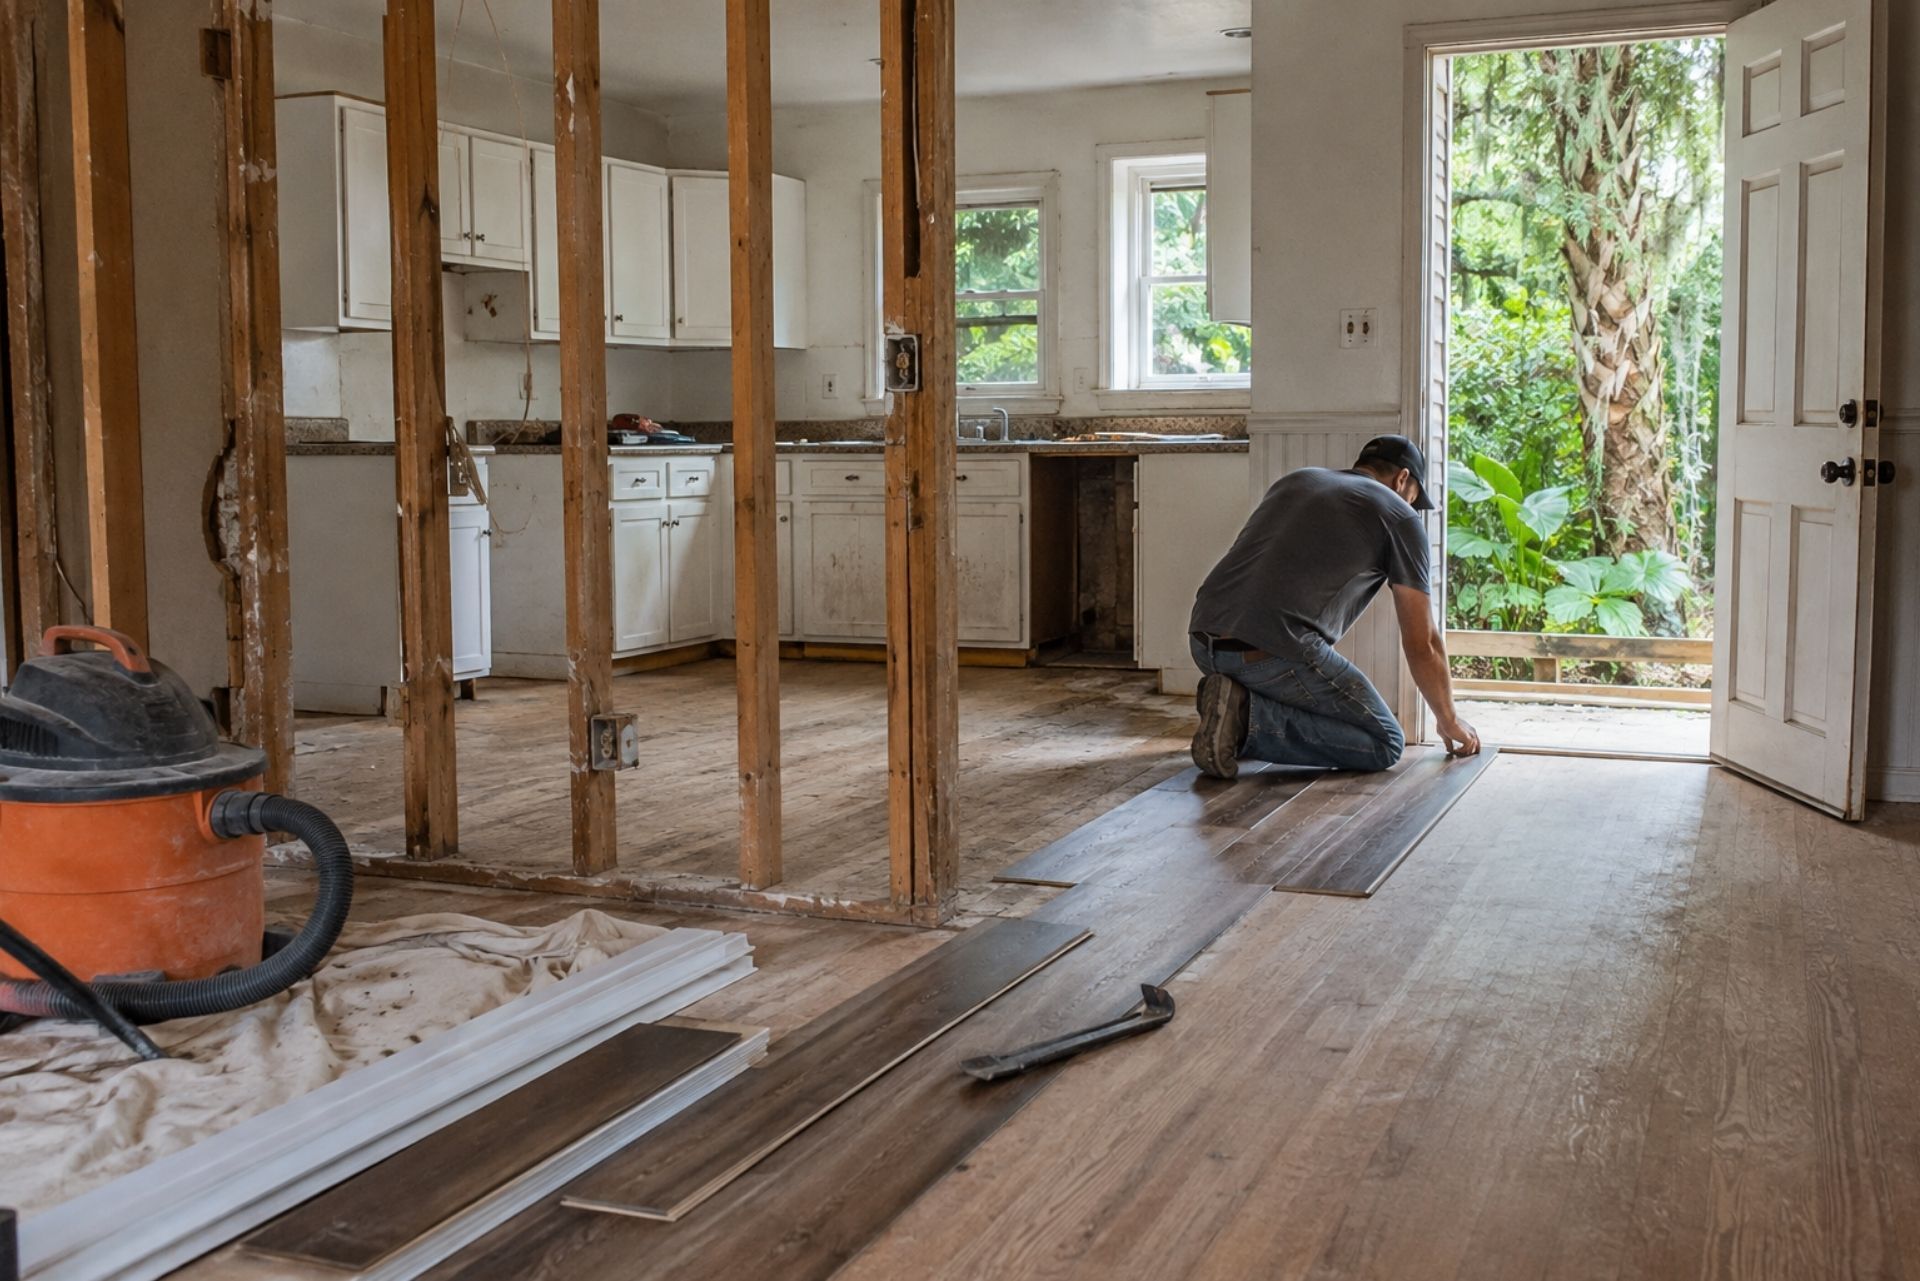
When you're gutting a house down to the studs, your standard policy won't cover it. Builders risk insurance is designed specifically for properties under construction or major renovation. It covers the structure, materials on-site, and often theft of building supplies. Construction risk policies bring structure to what is otherwise a chaotic exposure, protecting your investment during the most vulnerable phase of a flip. Policies are typically written for 3, 6, or 12-month terms, and builders risk coverage costs vary based on project scope, location, and construction type. Don't start demo without it.
Essential Liability and Income Protection
Property damage coverage is only half the equation. Liability exposure and income loss can be just as financially devastating, and they're often overlooked by investors focused on the physical structure.
Loss of Rents: Protecting Cash Flow During Repairs
If a covered loss makes your rental uninhabitable, loss of rents coverage reimburses the rental income you'd have collected during the repair period. For a property generating $1,800 per month, a six-month repair timeline after hurricane damage means $10,800 in lost income. Without this endorsement, that money simply evaporates. Most DP-3 policies offer loss of rents as an add-on, and blanket portfolio policies can cover it across multiple properties simultaneously.
Premises Liability for Multi-Family and Single-Family Units
A tenant slips on a wet staircase. A visitor's child falls through a rotted porch railing. These are the claims that generate five- and six-figure lawsuits. Premises liability coverage protects you against bodily injury and property damage claims arising from conditions on your rental property. For multi-family buildings, higher limits are essential: $1 million per occurrence with a $2 million aggregate is a common starting point. An umbrella policy on top of that provides an extra layer for investors with larger portfolios.
Common Questions About Louisiana Real Estate Insurance
Do I need flood insurance if my rental isn't in a high-risk zone?
Yes, you should strongly consider it. About 25% of flood claims in Louisiana come from properties outside high-risk flood zones. Premiums in moderate- and low-risk zones are often surprisingly affordable, sometimes under $500 per year.
How do I insure a house while it is being renovated?
You'll need a builders risk policy for the renovation period. Standard dwelling policies exclude damage related to construction activities. Builders risk covers the structure, materials, and often liability during the project. Your agent at a firm like Chabert Insurance can help you transition from builders risk back to a standard policy once the work is complete.
Will my insurance pay for lost rent after a hurricane?
Only if your policy includes loss of rents coverage. This isn't automatic on most investor policies. Check your declarations page for "fair rental value" or "loss of rents" language. If it's missing, add it before hurricane season.
Why is my windstorm deductible a percentage instead of a flat dollar amount?
Louisiana insurers use percentage-based wind deductibles to manage their catastrophic loss exposure. A 2% deductible on a $400,000 property means you pay the first $8,000 of any wind claim. This structure helps keep premiums lower than they'd be with flat deductibles, but it shifts more risk onto you.
Strategies for a More Resilient Portfolio
Building a durable insurance program for Louisiana rental properties isn't a one-time decision. It's an ongoing process that should evolve with your portfolio. Start by auditing your current policies for vacancy clauses, wind deductible percentages, and whether you're carrying ACV or RCV coverage. If you own five or more properties, ask your agent about blanket portfolio limits that cover all your buildings under a single policy with shared limits, which can simplify administration and reduce per-property costs.
Roof upgrades pay for themselves quickly in Louisiana. A new impact-resistant roof can cut wind premiums by 15% to 30% and reduce your exposure to percentage-based deductibles. Similarly, elevating mechanical systems in flood-prone properties can lower flood premiums and reduce the severity of future claims.
The 2026 rate decreases have created a real opportunity to restructure your coverage. Recent legislative shifts are allowing Louisiana property owners to lower premiums through new policy structures, and investors who act now can lock in favorable terms before the next active hurricane season changes the market again. Whether you're managing a handful of rentals in Mandeville or scaling a fix-and-flip operation across the Greater New Orleans area, the right insurance strategy protects both your properties and your ability to keep investing. Reach out to a local specialist like Chabert Insurance: The Ehrhardt Agency to review your portfolio and identify where you're overexposed or overpaying.
On this page
Fully licensed
Chabert Insurance: The Ehrhardt Agency is a fully licensed independent insurance agency serving individuals, families, and businesses across Louisiana and Mississippi.
From our offices in Mandeville and New Orleans, we proudly serve clients in Mandeville, Covington, New Orleans, Kenner, Metairie, Harahan, River Ridge, and Slidell, as well as the Westbank and St. Bernard Parish, and communities throughout Louisiana and Mississippi. As an independent agency, our team works with a wide range of top-rated carriers to provide personal and commercial coverage — home, auto, flood, commercial, life, and more — built around the real needs of the people and businesses we protect.
OTHER INSURANCE COVERAGE
About the Author
Ryan J. Ehrhardt
Owner / Licensed Agent
I'm Ryan J. Ehrhardt, owner and licensed agent at Chabert Insurance: The Ehrhardt Agency. I lead our team across our Mandeville and New Orleans offices, and I work with families and business owners every day to find coverage that fits their lives. I believe insurance should be simple to understand, so I take the time to explain your options in plain language before you decide.
As an independent agent, I answer to you, not to a single carrier. That means I can shop your policy across many companies and focus on what protects you best. When you call our office, you reach a real person who knows your account. I would be glad to review your coverage and help you feel confident about it.
[CONFIRM name]
Google review · Mandeville office
Home, Auto, Flood, Commercial & Life Insurance
Insurance built around your life in Louisiana
We compare coverage across many carriers and build one program that protects everything you own.
Home Insurance
Cover the cost to rebuild your house, replace your belongings, and answer a liability claim against your household.
Auto Insurance
Protect your vehicles with liability, collision, and uninsured motorist limits that hold up after a serious Louisiana wreck.
Flood Insurance
Your homeowners policy excludes flood. We quote NFIP and private options for your building and its contents.
Commercial Insurance
Liability, property, workers' compensation, and commercial auto for Louisiana businesses, priced against how your company operates.
Life Insurance
Replace the income your family depends on, with term and permanent options priced across several carriers.
Umbrella Insurance
Add a layer of liability protection above your auto and home limits, usually for a modest premium.
Ruston
Baton Rouge
Mandeville
Gretna
Louisiana Home Insurance
Home insurance built around where you live
Home insurance is our specialty. We write homeowners policies across Louisiana and price them against the wind, hail, and flood risk in your parish.
Areas we cover
Commercial Insurance for Louisiana Businesses
Coverage that keeps your business running
We build commercial programs around how your company actually operates, then compare carriers on price and claim service.
General Liability
Covers claims of bodily injury or property damage that come from your day-to-day operations.
Commercial Property
Protects your building, equipment, and inventory against fire, storm, theft, and other covered losses.
Workers' Compensation
Pays medical care and lost wages when an employee is hurt on the job, as Louisiana requires.
Commercial Auto
Covers the vehicles your business owns, along with the employees who drive them for work.
Professional Liability
Covers claims that your professional advice or services caused a client a financial loss.
Cyber Liability
Handles breach response, notification costs, and liability after customer data is exposed.
[CONFIRM name]
Google review · Mandeville office
Business Insurance by Industry
Specialized coverage for your line of work
Every trade carries its own risks. We know the coverage these Louisiana businesses need and where the gaps usually sit.
Plumbers
Liability, tools, and commercial auto coverage built for water damage claims and job-site risk.
Restaurants
Property, liquor liability, and spoilage coverage for kitchens, dining rooms, and your staff.
Real Estate Investors
Landlord property, liability, and vacancy coverage for rentals, flips, and multi-unit buildings.
[CONFIRM name]
Google review · Mandeville office
How to Get Insured in 4 Steps
Getting covered is simple
You talk to a licensed agent from the first call to the annual review.
1
Tell us about you
Share what you want to protect. A licensed agent asks about your home, vehicles, family, or business and gathers the details carriers need.
2
We shop our carriers
We compare options across the markets we represent and look at price, coverage limits, and how each carrier handles claims.
3
Review your choices
We explain coverage and price in plain language, side by side, so you can see the trade-offs before you choose.
4
Get covered
Your policy starts, you get your documents, and we review the coverage with you each year.
5-Star Rated by Louisiana Clients
What our clients say
Louisiana families and business owners rate us 5 stars for clear advice and fast answers.
139+ five-star reviews across our Mandeville and New Orleans offices