Variant Insurance Group is a licensed independent insurance agency in Minnesota. [CONFIRM license #.]
Get a Quote
Variant Insurance Group is a licensed independent insurance agency serving Minnesota families and businesses.
From our office in Maple Plain, our team works with many of Minnesota's top-rated carriers so your home, auto, life, and business coverage fits your real needs. We serve families and businesses across Minnesota.
Running a business on the Northshore means dealing with a unique mix of opportunities and risks. Between the steady foot traffic along Girod Street, the professional services clustered near the Causeway corridor, and the ever-present reality of hurricane season, Mandeville business owners face coverage decisions that differ sharply from those in other parts of the country. Understanding what business insurance you actually need - from general liability and business income protection to commercial flood and workers' compensation - can mean the difference between recovering from a setback and closing your doors for good. The stakes are real, and the details matter more than most owners realize until they're filing a claim. St. Tammany Parish has seen steady commercial growth over the past several years, and that growth brings both competition and exposure. Whether you're running a boutique on the downtown strip, managing a consulting practice, or operating a medical office, your insurance portfolio should reflect the specific risks tied to your location and industry. This guide breaks down the four coverage types that Mandeville businesses most commonly need and helps you understand how each one works in practice.
Navigating the Mandeville Business Landscape
Mandeville's business community is a mix of retail shops, restaurants, healthcare providers, law firms, and service contractors. Each of these business types carries its own risk profile, and a one-size-fits-all policy rarely provides adequate protection. The Northshore business community has made insurance a top priority in recent years, and for good reason: Louisiana's legal environment, weather patterns, and regulatory requirements create a coverage landscape unlike any other state.
Local agencies like Chabert Insurance: The Ehrhardt Agency work closely with Mandeville business owners to match policies to actual risk rather than selling generic packages. That local knowledge matters. A retail shop on Highway 190 faces different exposures than a CPA firm in an office park, and your policy should reflect those differences.
One thing to keep in mind is that Louisiana's commercial insurance market has been shifting. Several macro trends are affecting commercial insurance pricing in 2026, including rising reinsurance costs and increased claims frequency from weather events. Mandeville businesses that haven't reviewed their coverage recently may be underinsured without realizing it.
General Liability for Northshore Professionals and Retailers
General liability insurance is the foundation of almost every business insurance portfolio. It covers third-party bodily injury, property damage, and advertising injury claims - the kinds of lawsuits that can arise from everyday operations. For Mandeville businesses, general liability costs in Louisiana vary based on industry, revenue, and claims history, but most small businesses can expect to pay between $400 and $1,500 annually for basic coverage.
Effective August 1, 2026, Act 757 increased the minimum general liability insurance requirement for Louisiana contractors, which means businesses in the construction and trades sectors need to verify their policies meet the new thresholds. If you're a contractor working in St. Tammany Parish, this isn't optional - it's a licensing requirement.
Protecting Retail Storefronts from Slip-and-Fall Risks
Retail businesses in Mandeville see consistent foot traffic, especially in the Old Mandeville area and along the commercial corridors. Slip-and-fall claims are among the most common general liability incidents for storefronts. A customer trips over a wet floor, a loose threshold, or uneven pavement outside your entrance, and you're looking at medical bills, legal fees, and potential settlement costs.
Your general liability policy covers these claims, but the details matter. Make sure your policy includes adequate per-occurrence limits - most small retailers should carry at least $1 million per occurrence and $2 million aggregate. You should also confirm that your policy covers incidents on sidewalks and parking areas adjacent to your storefront, not just inside the building.
Professional Liability vs. General Liability for Consultants
Consultants, accountants, attorneys, and other professional service providers on the Northshore often assume their general liability policy covers everything. It doesn't. General liability protects against physical injuries and property damage, but it won't cover claims of professional negligence, errors in advice, or missed deadlines that cause a client financial harm.
That's where professional liability insurance (sometimes called errors and omissions coverage) fills the gap. If a client sues you because your consulting recommendation led to a financial loss, your general liability policy will deny the claim. You need a separate professional liability policy to cover those scenarios.
Comparison: General Liability vs. Professional Liability
Understanding the difference between these two coverage types prevents costly gaps. Here's a quick breakdown:
| Feature | General Liability | Professional Liability (E&O) |
|---|---|---|
| What it covers | Bodily injury, property damage, advertising injury | Errors, omissions, negligent advice |
| Common claims | Slip-and-fall, damaged client property | Missed deadlines, bad advice, contractual disputes |
| Required by law? | Often yes (for contractors, leases) | Depends on profession and licensing board |
| Typical annual cost | $400-$1,500 for small businesses | $500-$3,000 depending on profession |
| Coverage trigger | Physical incident or injury | Allegation of professional negligence |
Many Mandeville professionals need both policies. A local insurance provider familiar with Mandeville's business mix can help you determine the right combination based on your specific services and client contracts.
Protecting Your Revenue with Business Income Insurance
Most business owners insure their building and equipment but forget about the income those assets generate. Business income insurance - also called business interruption coverage - replaces lost revenue and covers ongoing expenses when a covered event forces you to shut down temporarily.
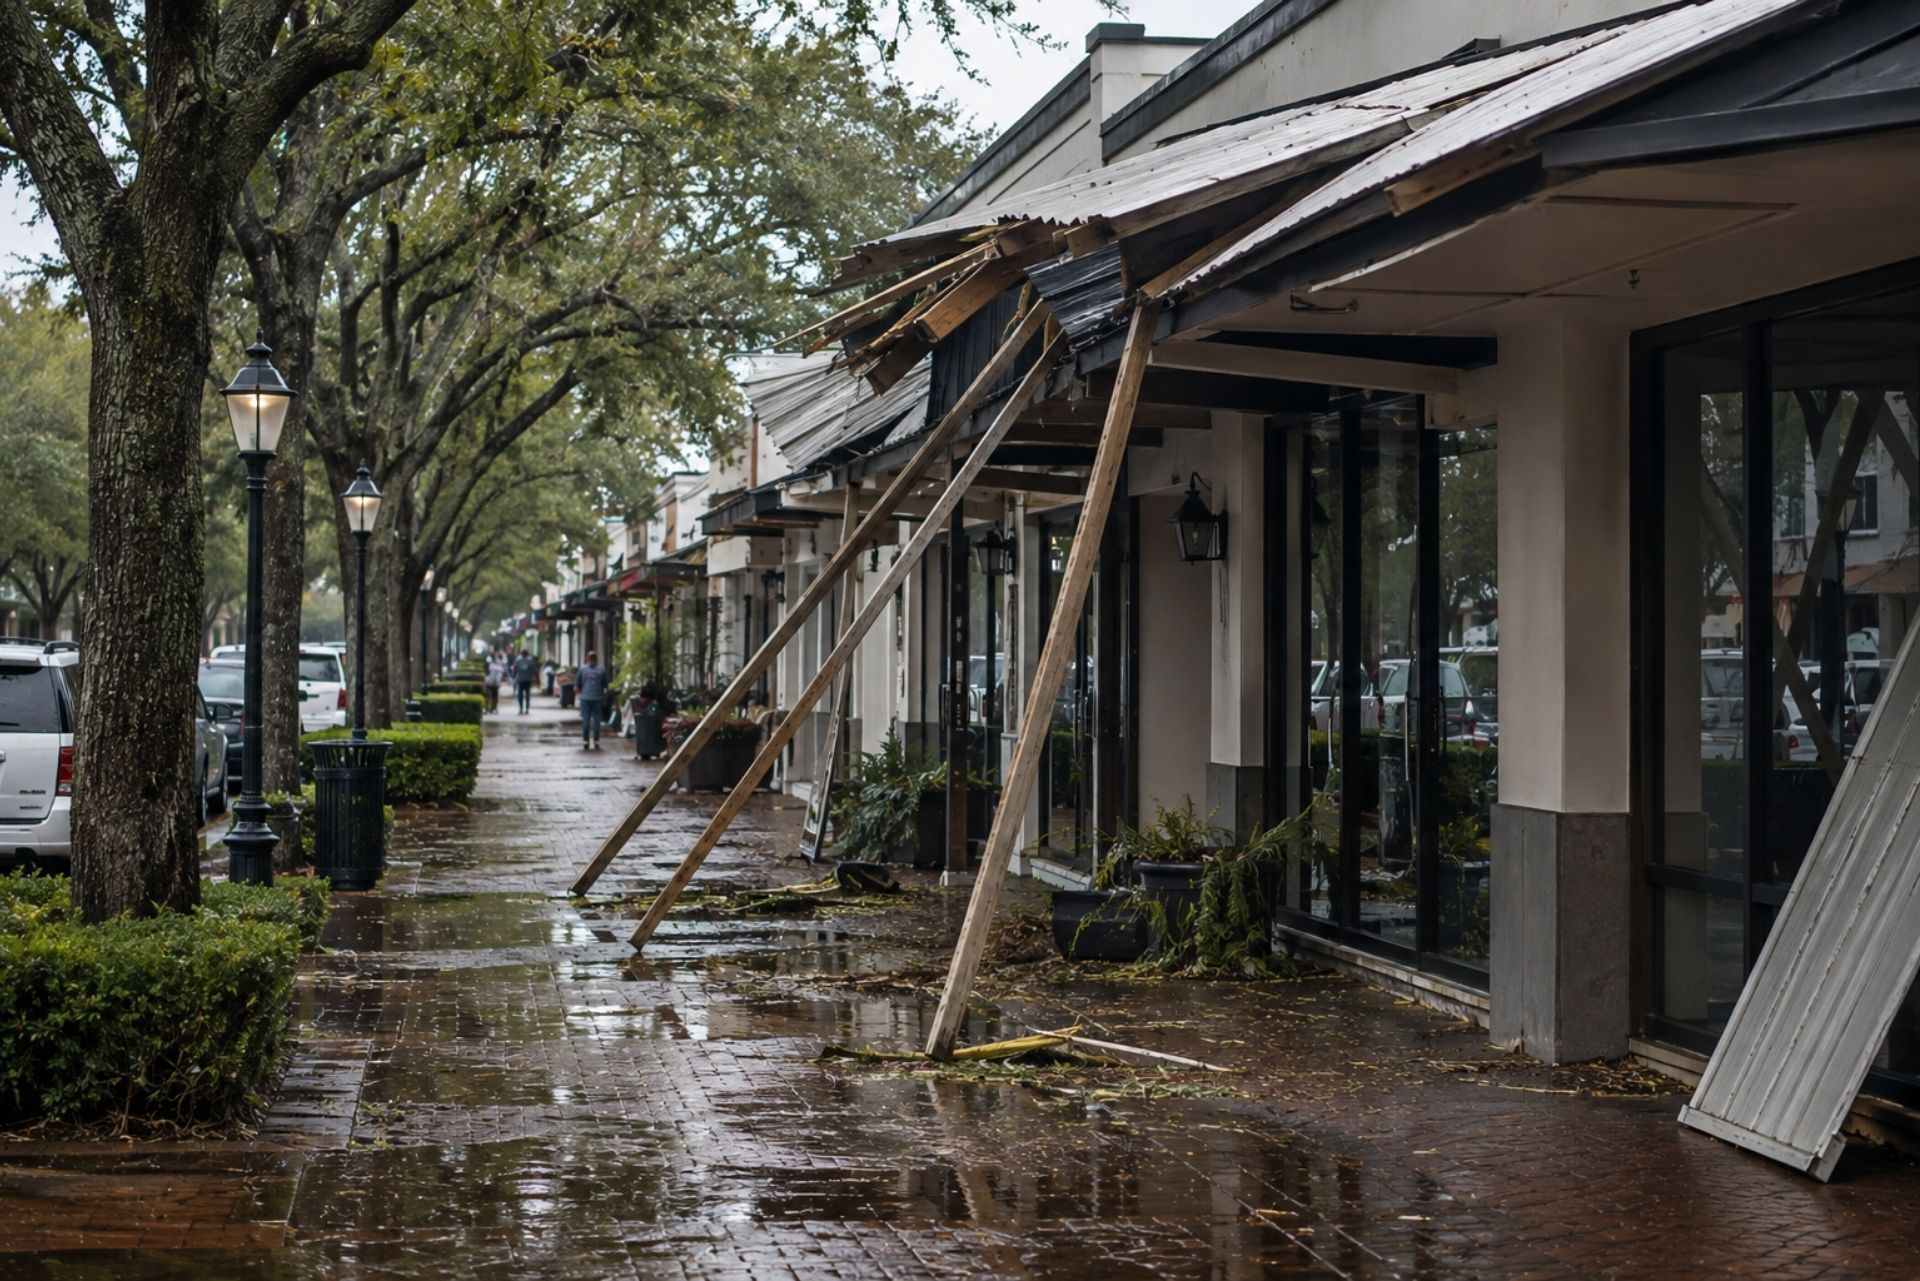
For Northshore businesses, this coverage is particularly relevant. A hurricane, fire, or major water damage event can close your doors for weeks or even months. During that time, your rent, loan payments, employee salaries, and utility bills don't stop. Business income insurance keeps those obligations covered while you rebuild.
How Business Interruption Coverage Works After a Loss
Business income coverage kicks in after a covered property loss triggers a shutdown. Here's the typical sequence: a fire damages your restaurant kitchen, your property insurance pays to repair the physical damage, and your business income policy covers the revenue you lose while repairs are underway.
The key phrase is "covered property loss." Your business income coverage is tied to your commercial property policy. If the event that caused the shutdown isn't covered by your property policy, your business income coverage won't activate either. This distinction becomes critically important when we talk about flood damage, which standard property policies exclude.
Covering Fixed Expenses and Payroll During Closures
The real value of business income insurance shows up in the details. A strong policy covers your fixed operating expenses: rent or mortgage, loan payments, taxes, and utilities. Many policies also cover payroll, which helps you retain trained employees who might otherwise find work elsewhere during a prolonged closure.
Some policies include "extended business income" coverage, which continues paying benefits even after you reopen if your revenue hasn't returned to pre-loss levels. This is especially useful for restaurants and retail shops that depend on customer habits - it can take months for foot traffic to return to normal after a major disruption. Ask your agent about the restoration period and whether your policy includes this extended benefit.
Commercial Flood Insurance in St. Tammany Parish
Flood risk isn't hypothetical in Mandeville - it's a documented, recurring reality. St. Tammany Parish has experienced multiple significant flood events in the past decade, and the parish's geography (low elevation, proximity to Lake Pontchartrain, and extensive bayou systems) makes commercial flood insurance essential for virtually every business.
Commercial insurance trends for spring 2026 indicate that flood coverage pricing continues to shift as FEMA updates its Risk Rating 2.0 methodology. Mandeville businesses should review their flood policies annually because premiums and coverage requirements can change even if your property hasn't.
Why Standard Property Policies Exclude Flood Damage
This catches many business owners off guard. Your commercial property insurance policy contains a flood exclusion - a standard clause that removes flood-related damage from coverage. It doesn't matter how comprehensive your property policy is; if rising water causes the damage, you need a separate flood policy to cover it.
The National Flood Insurance Program (NFIP) offers commercial flood policies with up to $500,000 in building coverage and $500,000 in contents coverage. For businesses that need higher limits, private flood insurance markets have expanded significantly in Louisiana. Chabert Insurance: The Ehrhardt Agency can help you compare NFIP and private flood options to find the best fit for your property's value and risk profile.
Understanding Flood Zones and Elevation Requirements
Your flood zone designation directly affects your premium and coverage requirements. Properties in high-risk zones (A and V zones) face higher premiums and may be required to carry flood insurance if they have a federally backed mortgage. Properties in moderate-risk zones (B and X zones) pay less but are by no means immune to flooding - roughly 25% of all flood claims come from properties outside high-risk zones.
Elevation certificates play a role in pricing too. If your building sits above the base flood elevation for your zone, you may qualify for lower premiums. If it sits below, expect to pay more. Getting an updated elevation certificate can sometimes reveal savings opportunities, especially if your property has been improved or if FEMA has revised the flood maps for your area.
Common Questions About Mandeville Business Coverage
Here are answers to the questions Mandeville business owners ask most often:
- Does my landlord's insurance cover my business? No. Your landlord's policy covers the building structure, not your business property, inventory, or liability. You need your own commercial policy.
- Is workers' compensation required in Louisiana? Yes, if you have one or more employees. Louisiana law requires workers' comp coverage for nearly all employers, with very few exceptions. Penalties for non-compliance include fines and personal liability for workplace injuries.
- Can I bundle general liability with property insurance? Yes. A Business Owner's Policy (BOP) combines general liability and commercial property coverage into a single policy, often at a lower cost than purchasing them separately. Most Mandeville small businesses qualify.
- How much general liability coverage do I need? Most small businesses should carry at least $1 million per occurrence. Landlords, clients, and contracts often require this as a minimum. Mandeville businesses can get customized quotes based on their specific industry and revenue.
- Does business income insurance cover pandemic-related closures? Generally no. Most business income policies require a direct physical loss to trigger coverage. Government-ordered closures without physical property damage typically aren't covered, though policy language varies.
- How long does it take to get flood insurance coverage? NFIP policies have a standard 30-day waiting period before coverage takes effect. Don't wait until a storm is in the Gulf to purchase your policy.
Making the Right Choice for Your Northshore Business
Getting the right insurance coverage for your Mandeville business isn't about buying the cheapest policy or checking a box. It's about matching your coverage to the specific risks you face based on your location, industry, and operations. General liability protects you from everyday accidents. Professional liability covers the advice and services you provide. Business income insurance keeps your revenue flowing during forced closures. And commercial flood insurance addresses the single biggest weather-related risk on the Northshore.
The best approach is to sit down with an agent who understands St. Tammany Parish and the Mandeville market specifically. Chabert Insurance: The Ehrhardt Agency offers the kind of personalized guidance that helps you build a coverage portfolio designed for your actual business - not a generic template. Review your policies at least once a year, especially before hurricane season, and don't assume last year's coverage still fits this year's needs. Your business has worked too hard to be left exposed by a gap you didn't know existed.
On this page
Fully licensed
Chabert Insurance: The Ehrhardt Agency is a fully licensed independent insurance agency serving individuals, families, and businesses across Louisiana and Mississippi.
From our offices in Mandeville and New Orleans, we proudly serve clients in Mandeville, Covington, New Orleans, Kenner, Metairie, Harahan, River Ridge, and Slidell, as well as the Westbank and St. Bernard Parish, and communities throughout Louisiana and Mississippi. As an independent agency, our team works with a wide range of top-rated carriers to provide personal and commercial coverage — home, auto, flood, commercial, life, and more — built around the real needs of the people and businesses we protect.
BUSINESS INSURANCE BY CITY
OTHER INSURANCE COVERAGE
About the Author
Ryan J. Ehrhardt
Owner / Licensed Agent
I'm Ryan J. Ehrhardt, owner and licensed agent at Chabert Insurance: The Ehrhardt Agency. I lead our team across our Mandeville and New Orleans offices, and I work with families and business owners every day to find coverage that fits their lives. I believe insurance should be simple to understand, so I take the time to explain your options in plain language before you decide.
As an independent agent, I answer to you, not to a single carrier. That means I can shop your policy across many companies and focus on what protects you best. When you call our office, you reach a real person who knows your account. I would be glad to review your coverage and help you feel confident about it.
[CONFIRM name]
Google review · Mandeville office
Home, Auto, Flood, Commercial & Life Insurance
Insurance built around your life in Louisiana
We compare coverage across many carriers and build one program that protects everything you own.
Home Insurance
Cover the cost to rebuild your house, replace your belongings, and answer a liability claim against your household.
Auto Insurance
Protect your vehicles with liability, collision, and uninsured motorist limits that hold up after a serious Louisiana wreck.
Flood Insurance
Your homeowners policy excludes flood. We quote NFIP and private options for your building and its contents.
Commercial Insurance
Liability, property, workers' compensation, and commercial auto for Louisiana businesses, priced against how your company operates.
Life Insurance
Replace the income your family depends on, with term and permanent options priced across several carriers.
Umbrella Insurance
Add a layer of liability protection above your auto and home limits, usually for a modest premium.
Ruston
Baton Rouge
Mandeville
Gretna
Louisiana Home Insurance
Home insurance built around where you live
Home insurance is our specialty. We write homeowners policies across Louisiana and price them against the wind, hail, and flood risk in your parish.
Areas we cover
Commercial Insurance for Louisiana Businesses
Coverage that keeps your business running
We build commercial programs around how your company actually operates, then compare carriers on price and claim service.
General Liability
Covers claims of bodily injury or property damage that come from your day-to-day operations.
Commercial Property
Protects your building, equipment, and inventory against fire, storm, theft, and other covered losses.
Workers' Compensation
Pays medical care and lost wages when an employee is hurt on the job, as Louisiana requires.
Commercial Auto
Covers the vehicles your business owns, along with the employees who drive them for work.
Professional Liability
Covers claims that your professional advice or services caused a client a financial loss.
Cyber Liability
Handles breach response, notification costs, and liability after customer data is exposed.
[CONFIRM name]
Google review · Mandeville office
Business Insurance by Industry
Specialized coverage for your line of work
Every trade carries its own risks. We know the coverage these Louisiana businesses need and where the gaps usually sit.
Plumbers
Liability, tools, and commercial auto coverage built for water damage claims and job-site risk.
Restaurants
Property, liquor liability, and spoilage coverage for kitchens, dining rooms, and your staff.
Real Estate Investors
Landlord property, liability, and vacancy coverage for rentals, flips, and multi-unit buildings.
[CONFIRM name]
Google review · Mandeville office
How to Get Insured in 4 Steps
Getting covered is simple
You talk to a licensed agent from the first call to the annual review.
1
Tell us about you
Share what you want to protect. A licensed agent asks about your home, vehicles, family, or business and gathers the details carriers need.
2
We shop our carriers
We compare options across the markets we represent and look at price, coverage limits, and how each carrier handles claims.
3
Review your choices
We explain coverage and price in plain language, side by side, so you can see the trade-offs before you choose.
4
Get covered
Your policy starts, you get your documents, and we review the coverage with you each year.
5-Star Rated by Louisiana Clients
What our clients say
Louisiana families and business owners rate us 5 stars for clear advice and fast answers.
139+ five-star reviews across our Mandeville and New Orleans offices